1800 121 5955
Key Takeaways
- A credit score is a single number, but the factors behind it—payment history, utilization, account age, hard inquiries, and derogatory marks—fail users when every metric competes for equal visual weight.
- Over half of executives report encountering misleading dashboards (Harvard Business Review), proving that hierarchy failures affect trained financial audiences and everyday consumers alike.
- Anchoring primary credit metrics to natural F- and Z-scanning patterns (Nielsen Norman Group) ensures users find the most consequential numbers without visual fatigue.
- Interactive dashboards increase user engagement by 48% (Gartner), while every $1 invested in UX design yields a $100 return (Forrester Research).
- Building compliance-first components, persistent ‘last updated’ timestamps, and human-in-the-loop AI confirmation states directly into the design system builds trust and reduces disputes.
Fintech dashboard design is the discipline of turning multi-variable financial intelligence into a clear hierarchy that users can understand and act on immediately. A credit score is a single number, but everything behind it is not: payment history, credit utilization, account age, hard inquiries, and derogatory marks each carry distinct weightings and regulatory caveats. Presenting all of that on one screen is where most financial products quietly lose their users.
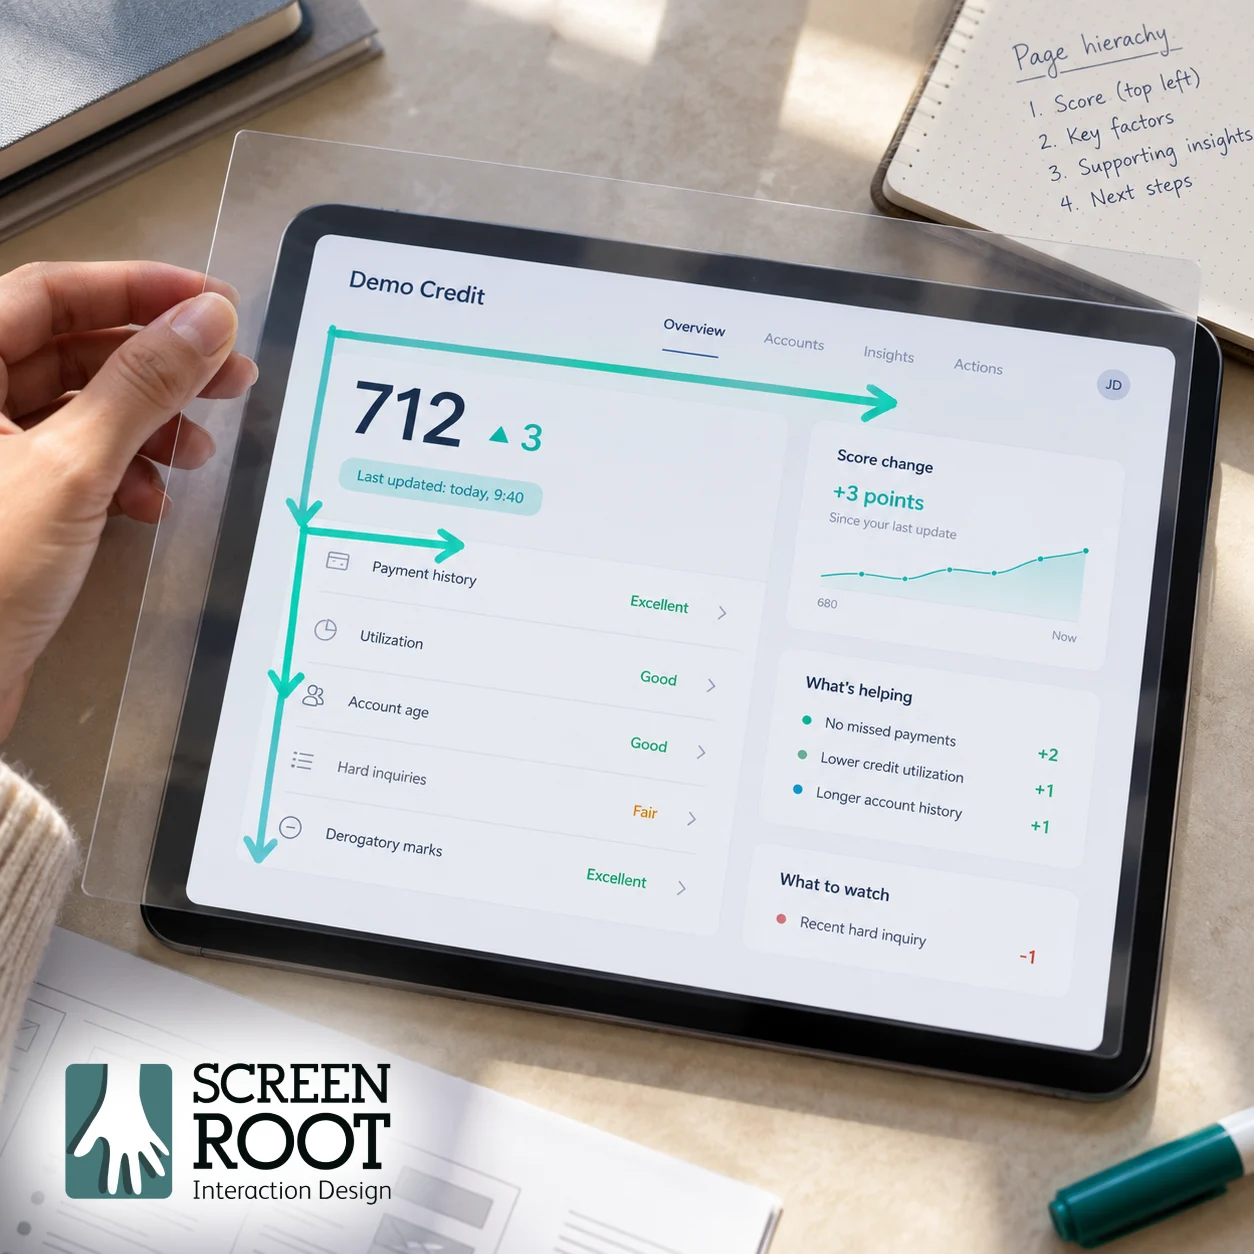
The failure is rarely a lack of data; it is the absence of hierarchy. When every metric competes for equal attention, the interface stops being informative and starts being exhausting. Eye-tracking research from the Nielsen Norman Group shows that users scan dashboards in predictable F and Z patterns, meaning the top-left region and the first horizontal sweep carry disproportionate weight. Fill those zones with decorative branding or secondary metrics, and the most consequential number on the screen gets discovered by accident.
This is not a theoretical risk. According to Harvard Business Review, over half of executives have encountered misleading dashboards, which reveals how widespread presentation failures are even among audiences trained to interrogate numbers. If a CFO can be misled by a chart, a consumer checking whether their credit score moved three points is working with far less defense. Experian faced this exact challenge: an industry-leading credit intelligence engine paired with an interface that made that intelligence hard to act on. Because Forrester Research shows that every $1 invested in UX design yields a $100 return and Gartner data proves interactive dashboards increase user engagement by 48%, the business case for fixing it was never in doubt. The question was method, not justification.
What is fintech dashboard design, and why do regulated dashboards fail?
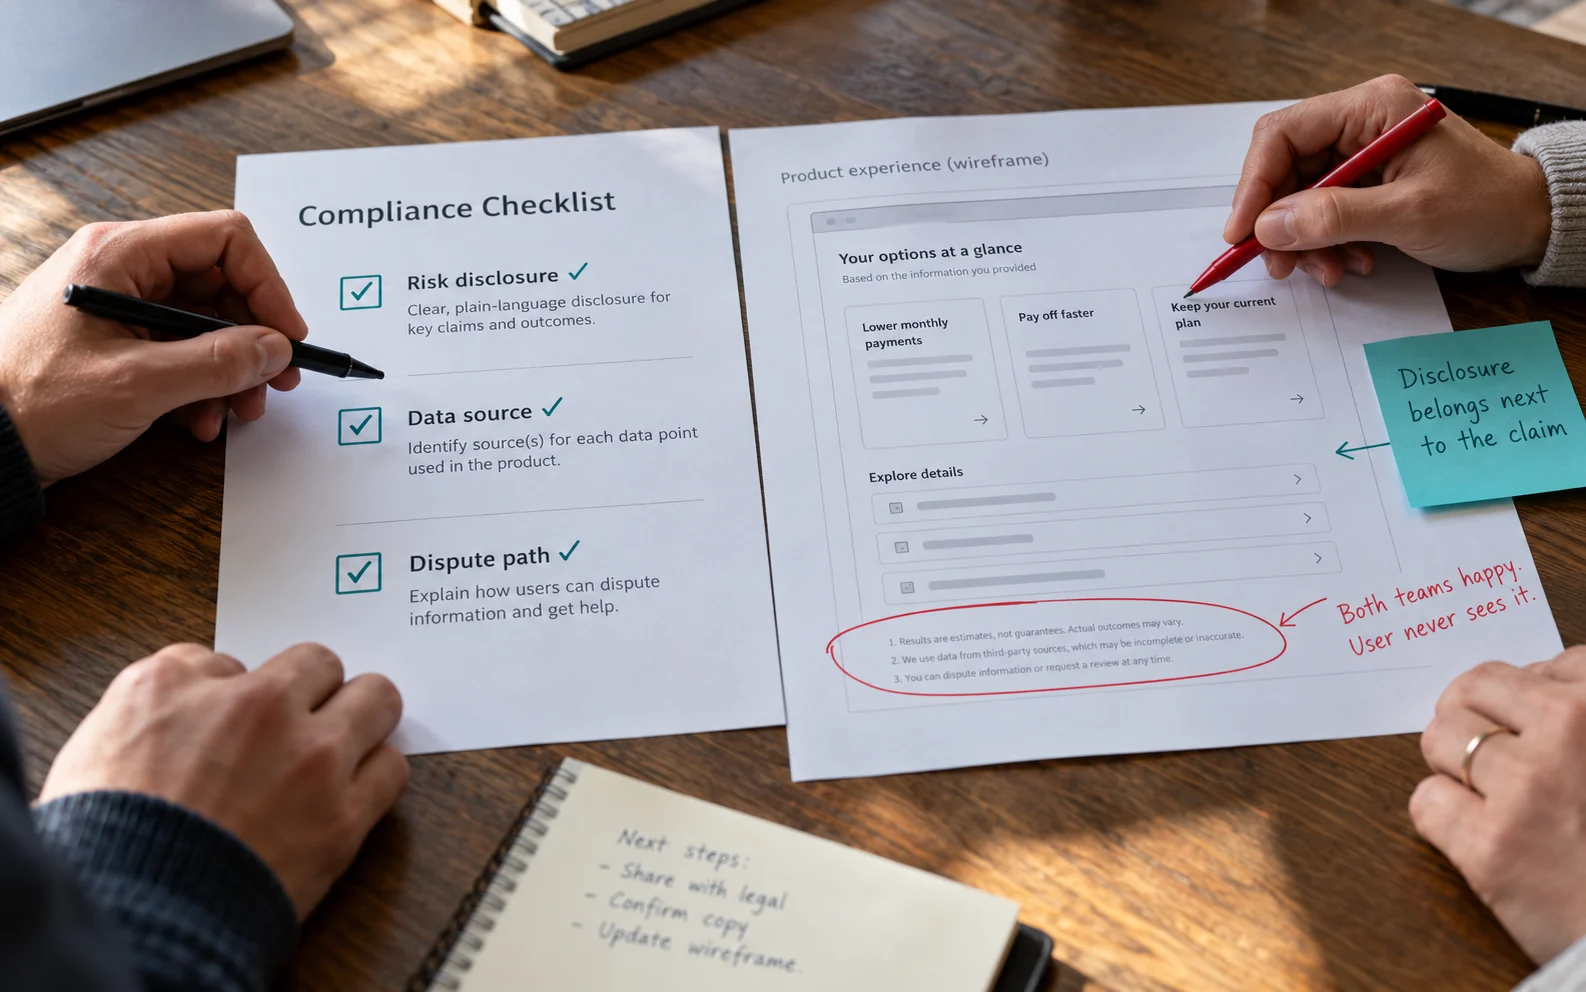
Fintech dashboard design is the structured presentation of financial metrics, historical trends, risk indicators, and regulatory disclosures within an interactive interface that supports confident financial decision-making. In regulated industries, dashboards fail when designers and compliance teams treat statutory disclosures and user clarity as opposing goals.
A credit dashboard carries mandatory risk disclosures, data-source attributions, and dispute pathways that cannot be buried in a settings menu. Compliance teams rightly insist on their presence. Designers, left to resolve that tension alone, usually solve it by stacking warnings at the bottom of the screen where nobody reads them. Both internal parties get what they asked for, while the user gets neither clarity nor protection. Effective financial dashboard design resolves that conflict by treating regulatory context as a core part of the visual architecture.
How did a research-first approach transform the Experian credit score dashboard UI?
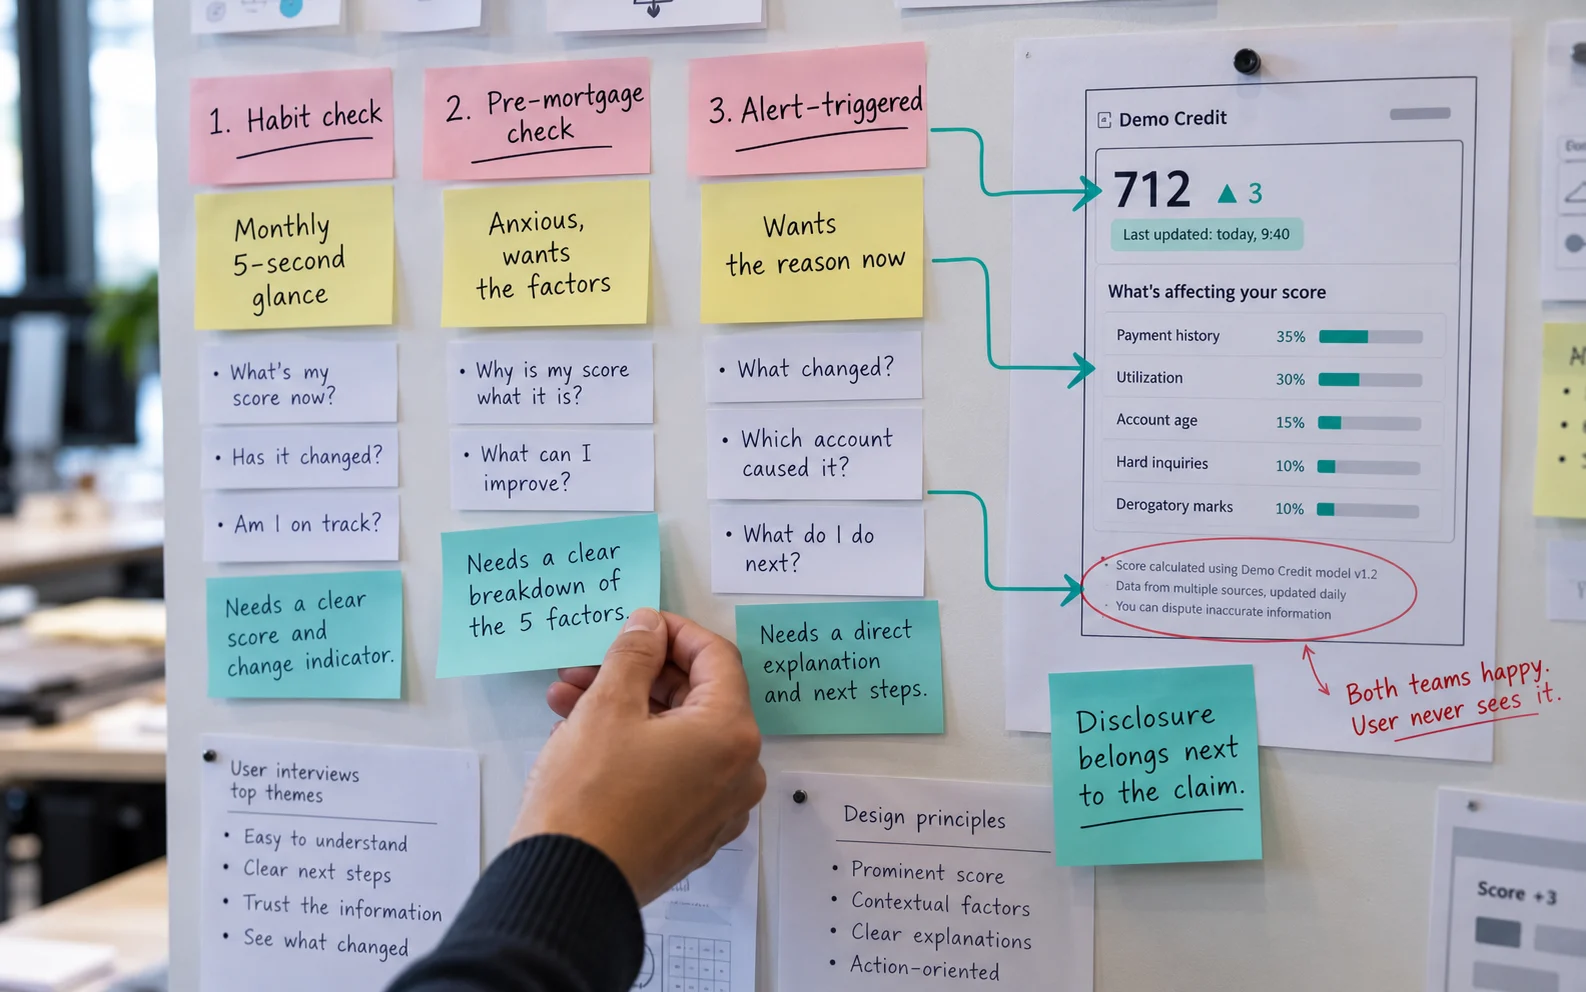
A research-first approach transformed the Experian credit score dashboard UI by starting with observed user behavior and intent rather than mood boards or visual trends. Before a single screen was drawn, ScreenRoot mapped what users actually did with their credit information: who checked monthly out of habit, who checked frantically before a mortgage application, and who opened the app only after receiving an alert.
Those three user intents demand distinct information paths, and a single flat aesthetic treatment serves none of them well. Layout decisions followed directly from Nielsen Norman Group scanning research. Because users scan dashboards in F and Z patterns, the primary credit score and its directional movement were anchored where the eye lands first, with contributing factors arranged along the natural sweep rather than competing for the same real estate. That structural discipline does more for comprehension than any color palette.
Three structural interventions carried the most weight in this Experian case study:
- Compliance-first components. Mandatory risk language and data-source attribution were treated as design elements with defined positions and contrast ratios, not as legal text appended after sign-off. Disclosures sit directly adjacent to the claims they qualify, satisfying the regulator and informing the user in the same gesture.
- Explicit data freshness indicators. Credit bureau data refreshes on its own schedule, and users routinely mistake stale figures for current ones. A persistent ‘last updated’ timestamp on every score panel removed an entire category of support tickets and, more importantly, an entire category of misplaced distrust.
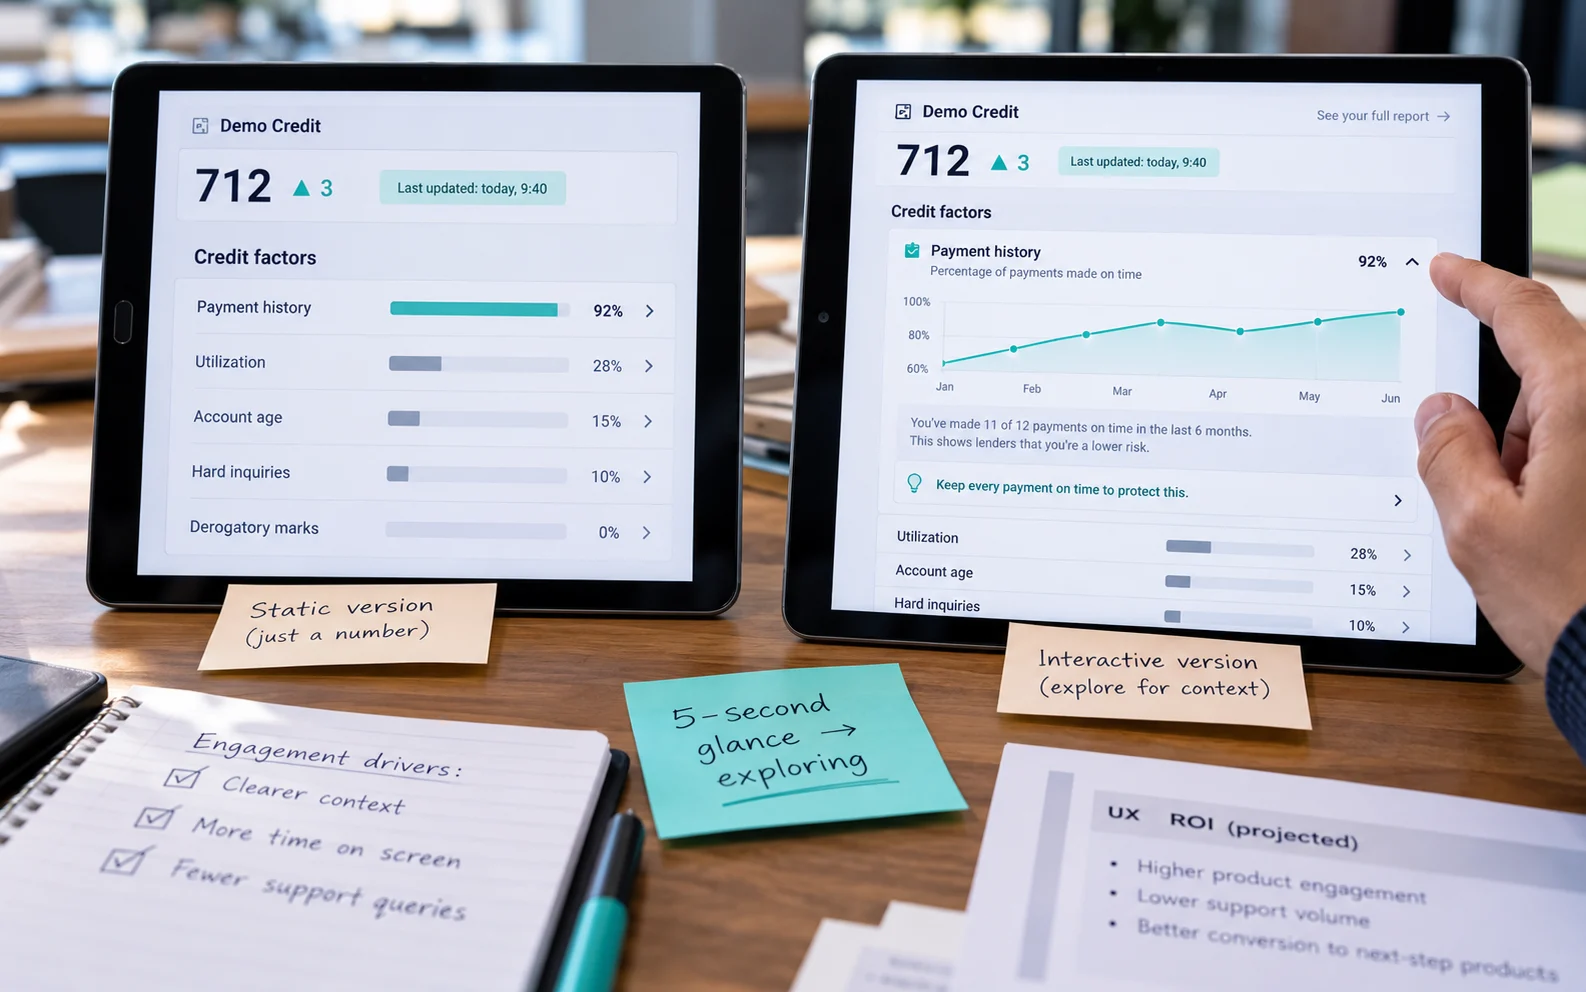
- Progressive disclosure of credit factors. Rather than displaying all scoring factors simultaneously in a dense wall of text, each factor expands on demand into its own plain-language explanation, historical trend, and improvement guidance. The summary stays readable while the depth stays available.
None of this was friction-free. Compliance and clarity pulled against each other on nearly every screen, and the resolution was negotiated component by component rather than settled all at once.
How do interactive dashboards drive user engagement and UX ROI?
Interactive dashboards drive engagement and ROI by shifting users from passive score checking to active investigation of the factors behind their financial standing. Gartner research demonstrates that interactive dashboards increase user engagement by 48%, while Forrester Research establishes that every $1 invested in UX design yields a $100 return.
In the Experian redesign, sessions shifted from quick five-second glances to genuine exploration of the factors beneath the number—the exact behavior a credit intelligence business wants. A static report became an interactive tool. When a credit factor can be expanded, compared across months, and connected to a specific action, users stay to investigate. When it is a flat label next to a percentage, they leave.
| Design Dimension | Static Legacy Report | Interactive Research-Led Dashboard |
| Visual scanning path | Competing metrics and banners in the top-left zone | F- and Z-pattern hierarchy anchoring primary score and delta |
| Credit factor depth | Flat percentages with no clear link to action | Expandable progressive disclosure with multi-month trends |
| Compliance & attribution | Stacked legal boilerplate at the bottom of the view | Modular compliance components adjacent to qualified claims |
| Data currency | Unlabeled refresh intervals causing user doubt | Persistent ‘last updated’ timestamps on every score module |
That 1:100 UX return ratio reframes design spend as capital allocation rather than cosmetic overhead. For a product whose entire value proposition is helping people understand and improve a financial position, interface quality is not adjacent to the business model—it is the business model. Visible timestamps, plainly worded disclosures, and contextual explanations signaled competence, making users far more willing to act on recommendations and far less likely to file disputes out of confusion.
How do you future-proof banking dashboard design for agentic AI and real-time data?
Future-proofing banking dashboard design and personal finance dashboard design requires transparent reasoning for autonomous AI actions, human-in-the-loop confirmation states, and honest UI states for broken or lagging connections. As agentic AI enters retail financial products faster than standard design patterns, interfaces must show their work.
Visualizing autonomous actions
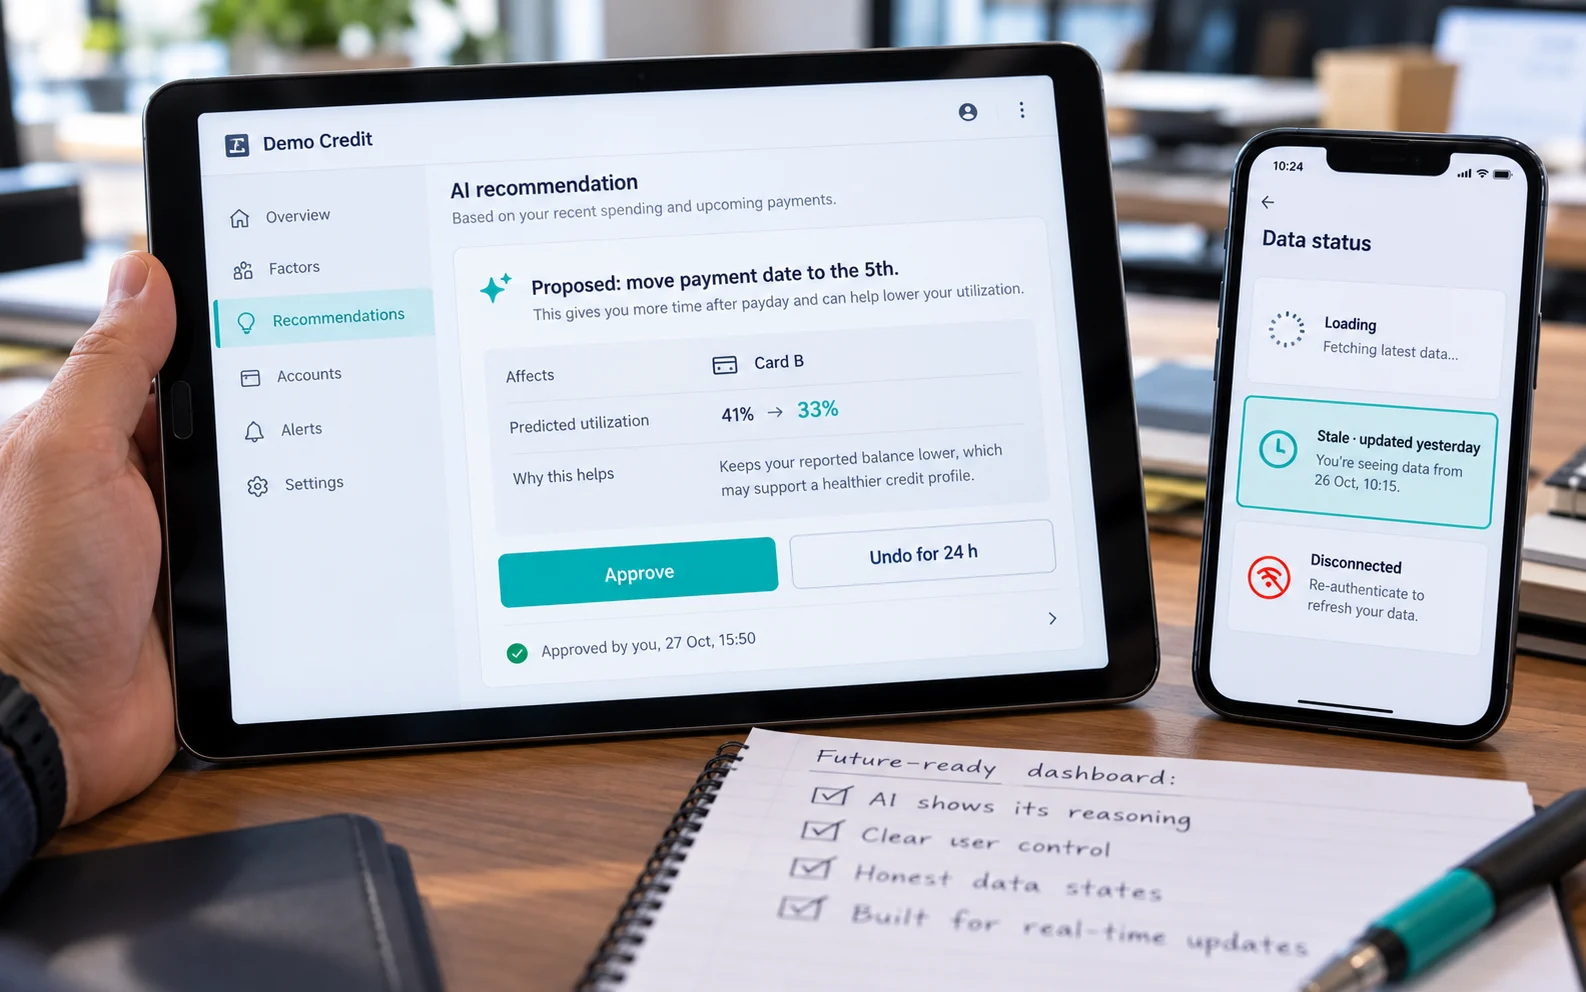
When an agentic system proposes to rebalance a debt payoff order or shift a payment date, the credit score dashboard UI has to show its reasoning, not just its conclusion. A recommendation card that states what the agent intends to do, which accounts it affects, and what it predicts will change gives the user something concrete to evaluate. A card that simply says ‘Optimized’ gives them nothing but a reason to be suspicious.
Human-in-the-loop confirmation states
Autonomy without a safeguard is a liability in any regulated product. Build explicit confirmation states for anything the system initiates on the user’s behalf: a clear preview, a reversible window, and a plain-language record of what was approved and when. This serves two masters at once: users get control, and compliance gets an audit trail that does not require engineering archaeology to reconstruct.
Designing for real-time and broken connections
Live data brings live failure modes. Skeleton loaders should mirror the exact shape of the content they are replacing so the layout does not jump when figures arrive and users can begin orienting before the numbers land. Generic spinners communicate only delay. When an open-banking aggregator link stalls or a bank requires re-authentication, the dashboard must distinguish clearly between ‘this number is loading,’ ‘this number is stale,’ and ‘this account is disconnected.’ Collapsing all three into a blank state erodes trust.
What are the key takeaways for fintech product leaders in 2026?
For executives weighing a legacy interface overhaul against competing capital priorities, the Experian engagement distills into four decisions worth making early:
- Let research set the layout, not aesthetic trend. Eye-tracking behavior determines where critical financial metrics belong on the screen. Establish the information hierarchy first, then apply the brand system to it.
- Treat interactivity as an engagement lever, not a feature request. Expandable factors, comparative views, and on-demand explanations convert passive readers into active investigators. In personal finance dashboard design, the difference between a user who glances and a user who explores is the difference between a monthly open and a daily habit.
- Build compliance into the component library. Mandatory disclosures, data attributions, and risk language should have defined positions, contrast standards, and reusable patterns placed adjacent to the claims they qualify. Appending legal copy to a finished design produces screens that satisfy neither the regulator nor the user.
- Budget UX as a return-generating investment. Reduced support volume, higher retention, and fewer disputes driven by confusion all accrue to the same interface decisions. Regulatory obligation and user clarity only become opposed when design treats compliance as an afterthought.
How should product teams interpret industry UX benchmarks and sources?
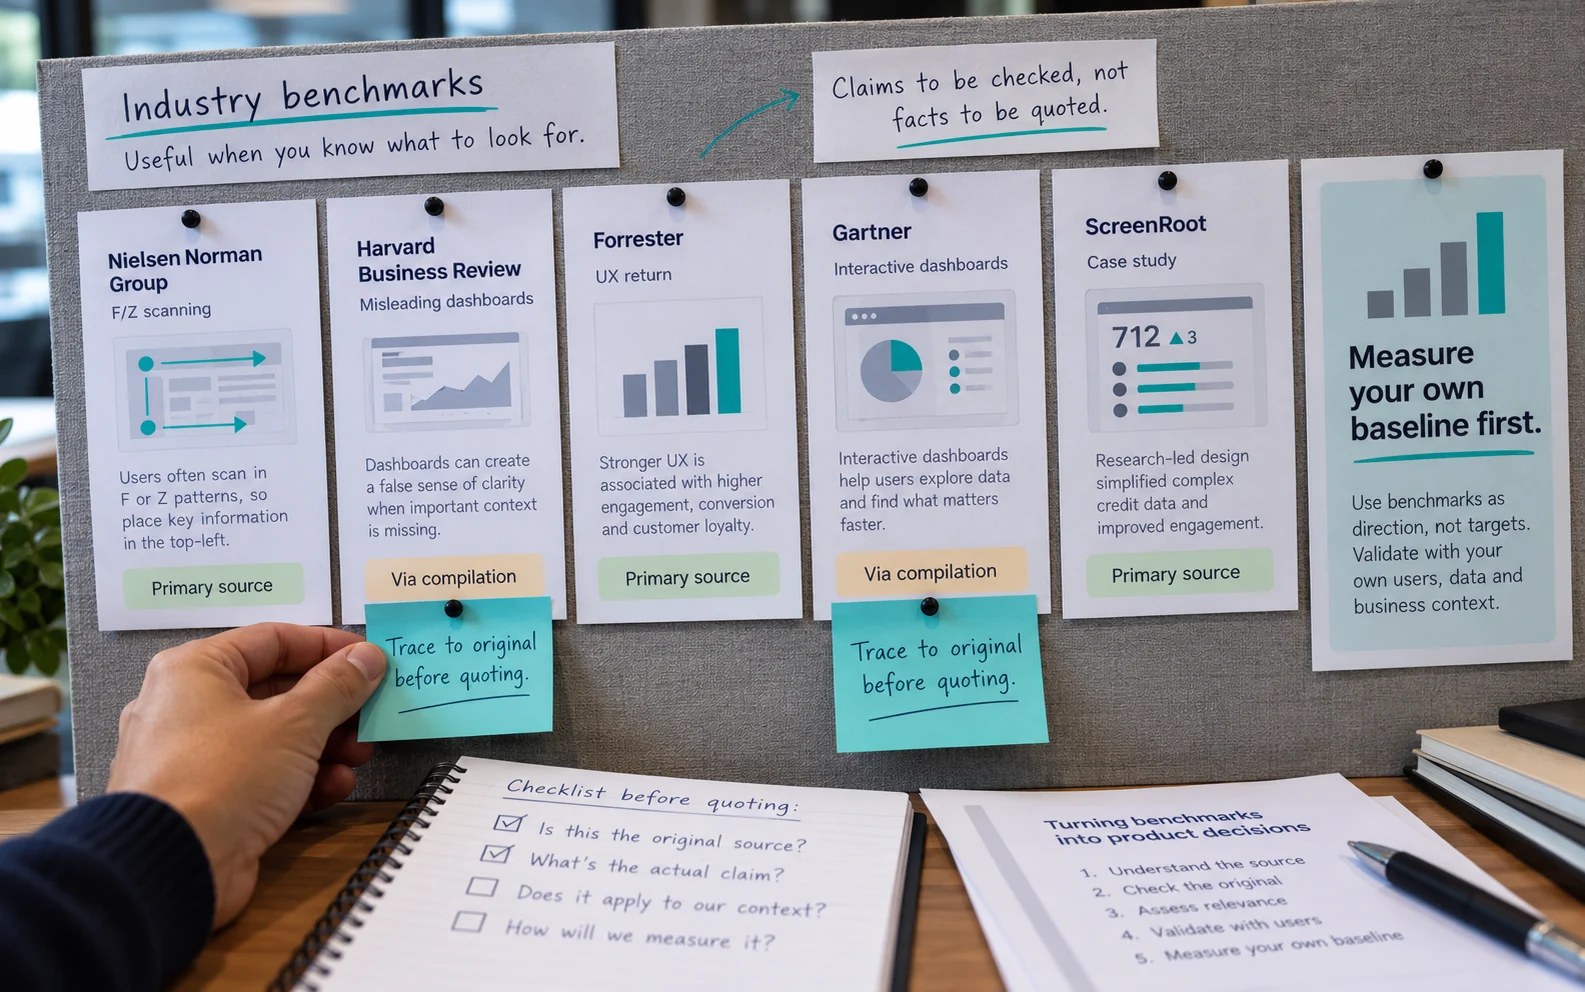
Industry-wide UX benchmarks establish that data presentation problems are structural rather than idiosyncratic, helping product leaders size an opportunity before committing capital. They are not, however, a substitute for instrumenting your own baseline before a redesign begins.
- Forrester Research: Data showing every $1 invested in UX design yields a $100 return, framing interface engineering as capital allocation (referenced via Maze’s UX statistics compilation).
- Nielsen Norman Group: Eye-tracking research on F- and Z-pattern visual scanning that informed the placement of primary credit metrics and contributing factors.
- Harvard Business Review: Survey data showing over half of executives have encountered misleading dashboards, proving presentation flaws impact sophisticated users.
- Gartner: Research establishing that interactive dashboards increase user engagement by 48% over static displays (referenced via Webtonic’s fintech dashboard analysis).
- ScreenRoot: The Experian credit score UI design case study covering behavioral research, compliance-first components, data freshness indicators, and progressive disclosure.
Frequently Asked Questions
What makes a good fintech dashboard design?
A good fintech dashboard design establishes a clear visual hierarchy aligned with F- and Z-scanning patterns, uses progressive disclosure to prevent cognitive overload, displays explicit ‘last updated’ timestamps, and places regulatory disclosures directly adjacent to the financial metrics they qualify.
How do interactive dashboards affect user engagement in financial apps?
According to Gartner, interactive dashboards increase user engagement by 48%. Allowing users to expand credit scoring factors, compare multi-month trends, and view actionable guidance turns a static monthly report into a tool users explore regularly.
What is the ROI of UX design in financial services?
Forrester Research found that every $1 invested in UX design yields a $100 return. In fintech and banking products, this return comes from higher customer retention, faster feature adoption, lower support ticket volume, and fewer customer disputes caused by confusing data.
How should banking dashboard design handle broken connections or stale data?
Banking dashboard design should use layout-matching skeleton loaders during fetches and clearly separate ‘loading,’ ‘stale data,’ and ‘disconnected account’ states with persistent timestamps and inline re-authentication prompts so users never mistake a stalled feed for a zero balance.
How do you integrate compliance disclosures without cluttering a credit score dashboard UI?
Build compliance-first components directly into the design system with defined positions and WCAG-compliant contrast ratios. Place concise risk language and bureau attributions next to the specific claims they qualify rather than stacking legal text at the bottom of the screen.
Ready to turn complex financial data into an engagement engine?
If your platform has strong underlying financial intelligence trapped behind a dense or static interface, the next step is a research-led diagnostic. Explore ScreenRoot’s BFSI case studies at screenroot.com/work/, or talk to our team about running a UX audit on your core customer dashboard.
Written by Team ScreenRoot. 16+ years leading enterprise UI/UX research for BFSI, SaaS, and Healthcare clients.
When you’re ready, let’s talk.
📞 Call us (Toll-Free): 1800 121 5955 (India)
✉️ Email us: [email protected]