1800 121 5955
Key Takeaways
- The feature parity war is over; personalized customer experience quality is the new differentiator.
- Bank adoption of Generative AI will grow from 5% to over 80% by 2026 (Gartner).
- Systemic UX treats back-end compliance decisions as design surfaces, reducing customer drop-off.
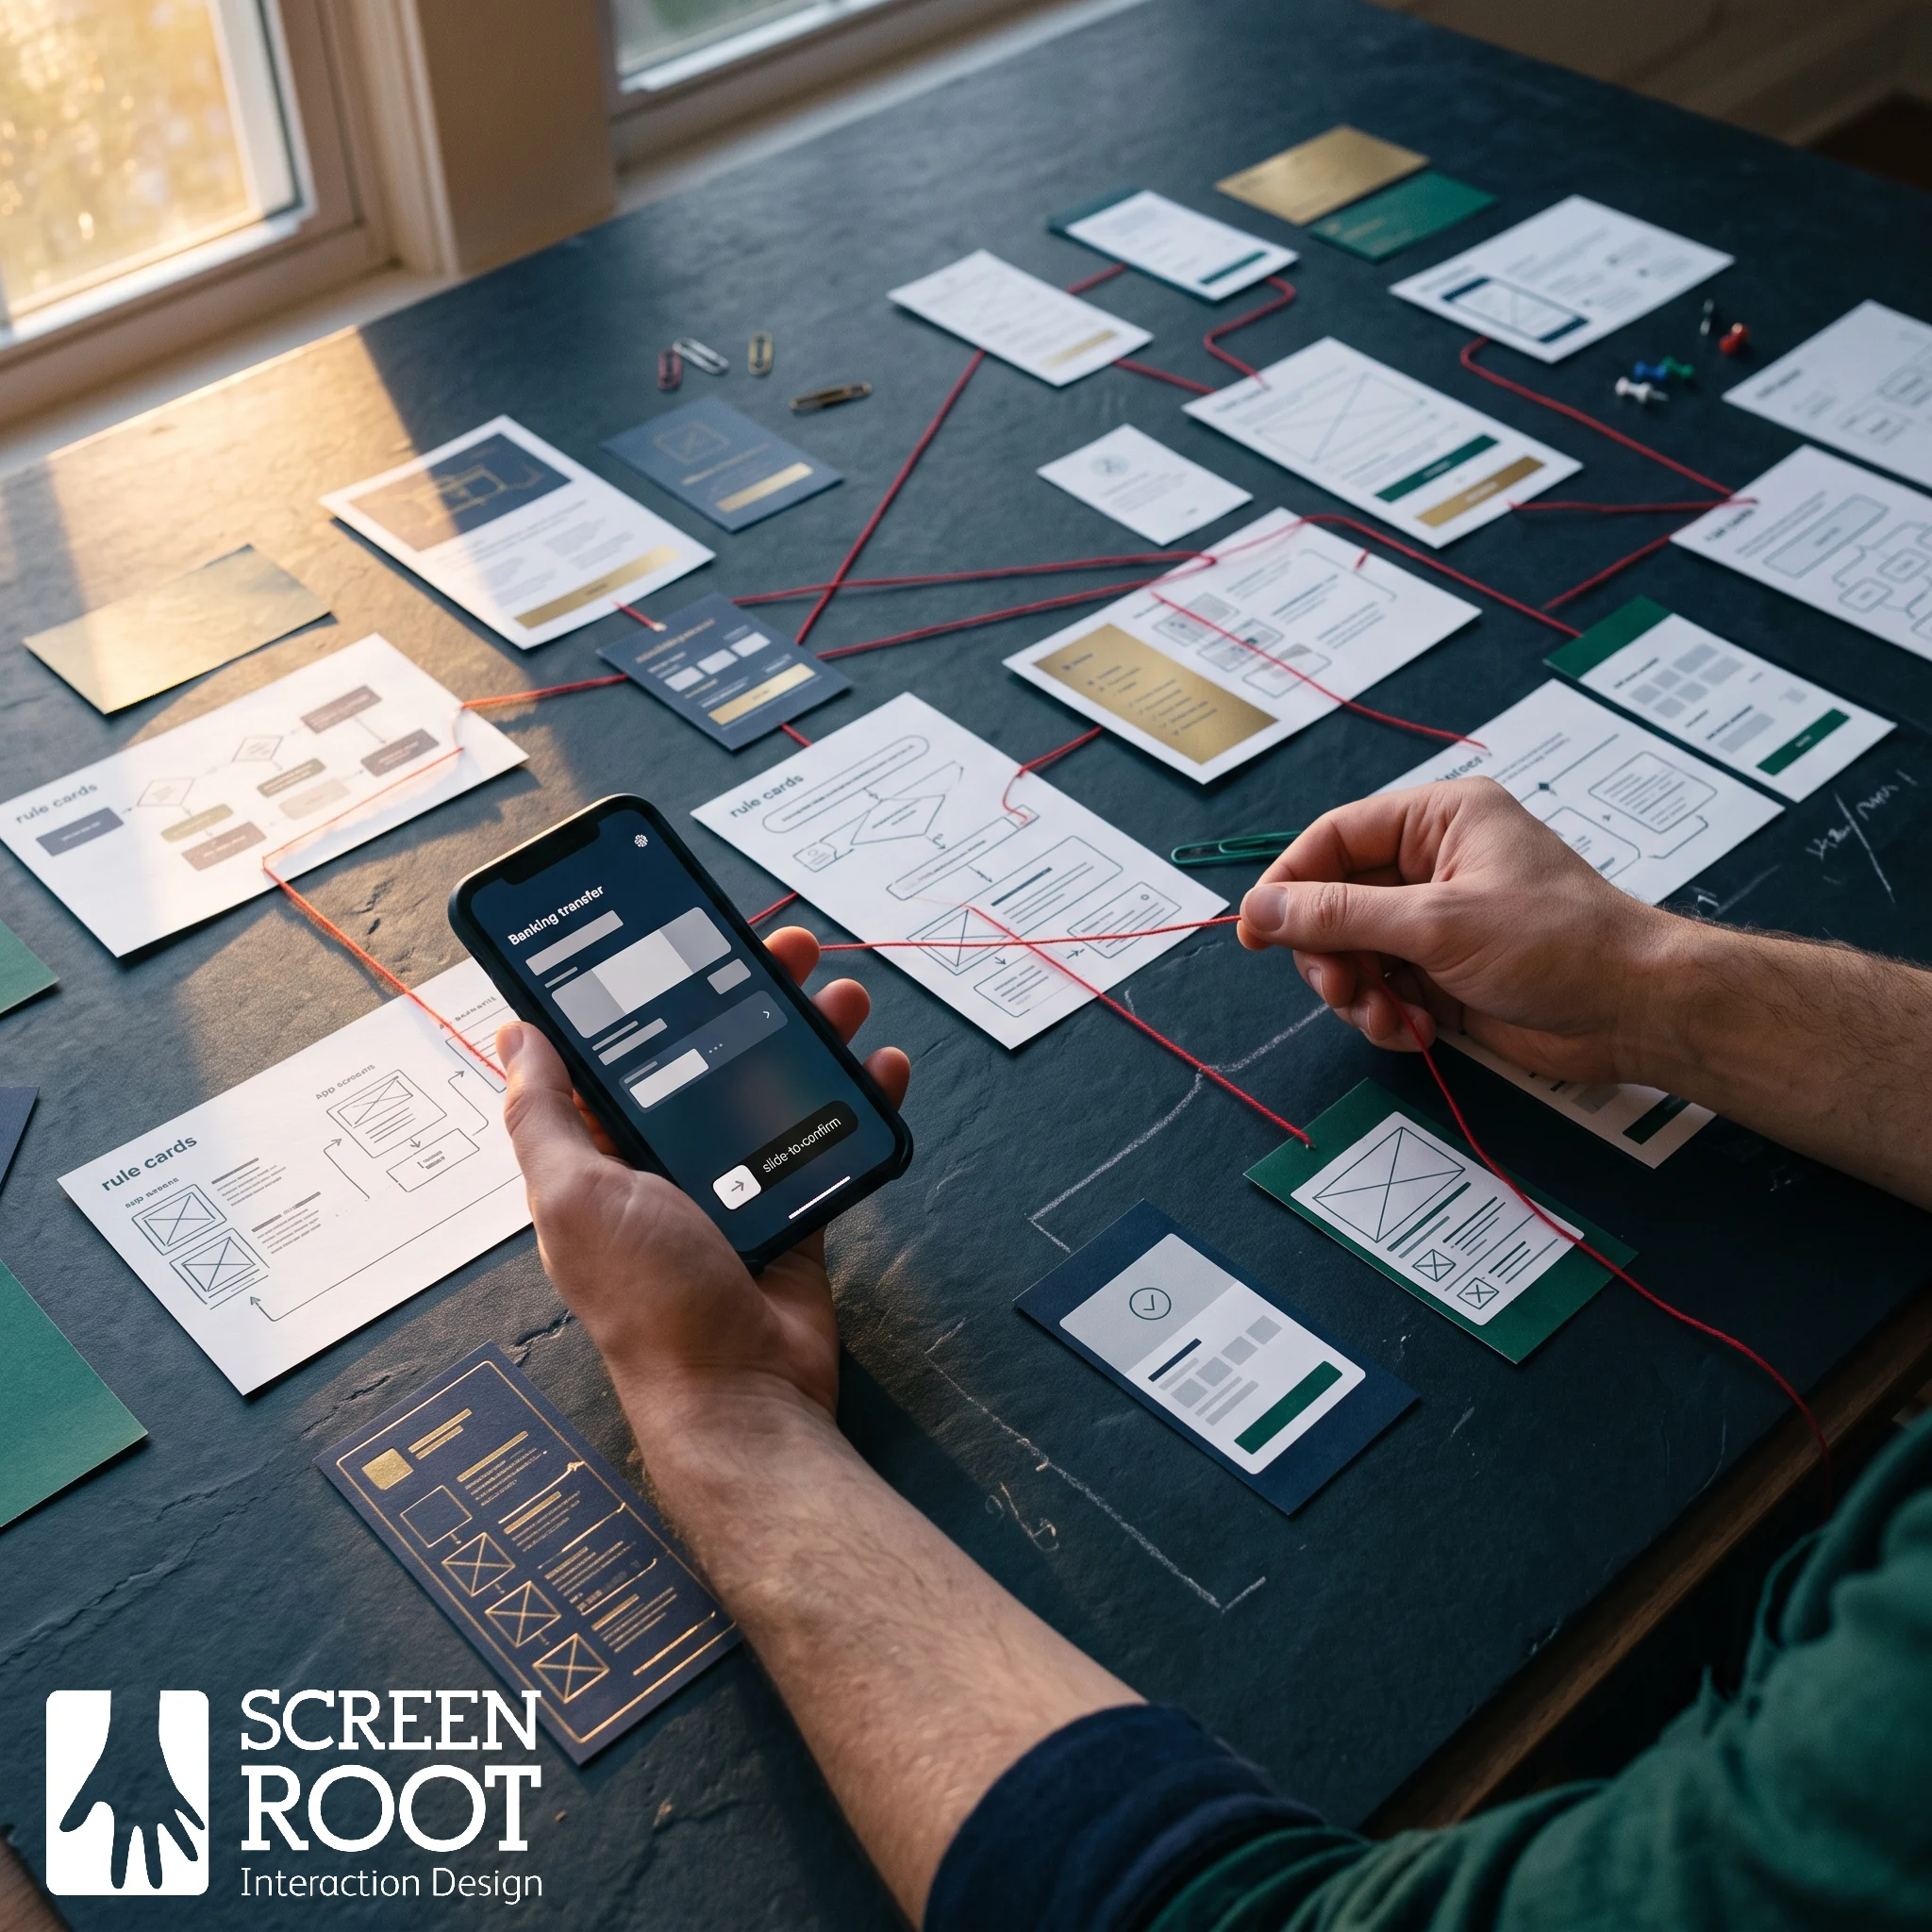
- The Smart Friction Framework intentionally slows down irreversible actions to build user trust.
- Humanizing KYC transforms mandatory compliance hurdles into trust-building onboarding interactions.
What Are the Top Financial Services UX Challenges Today?
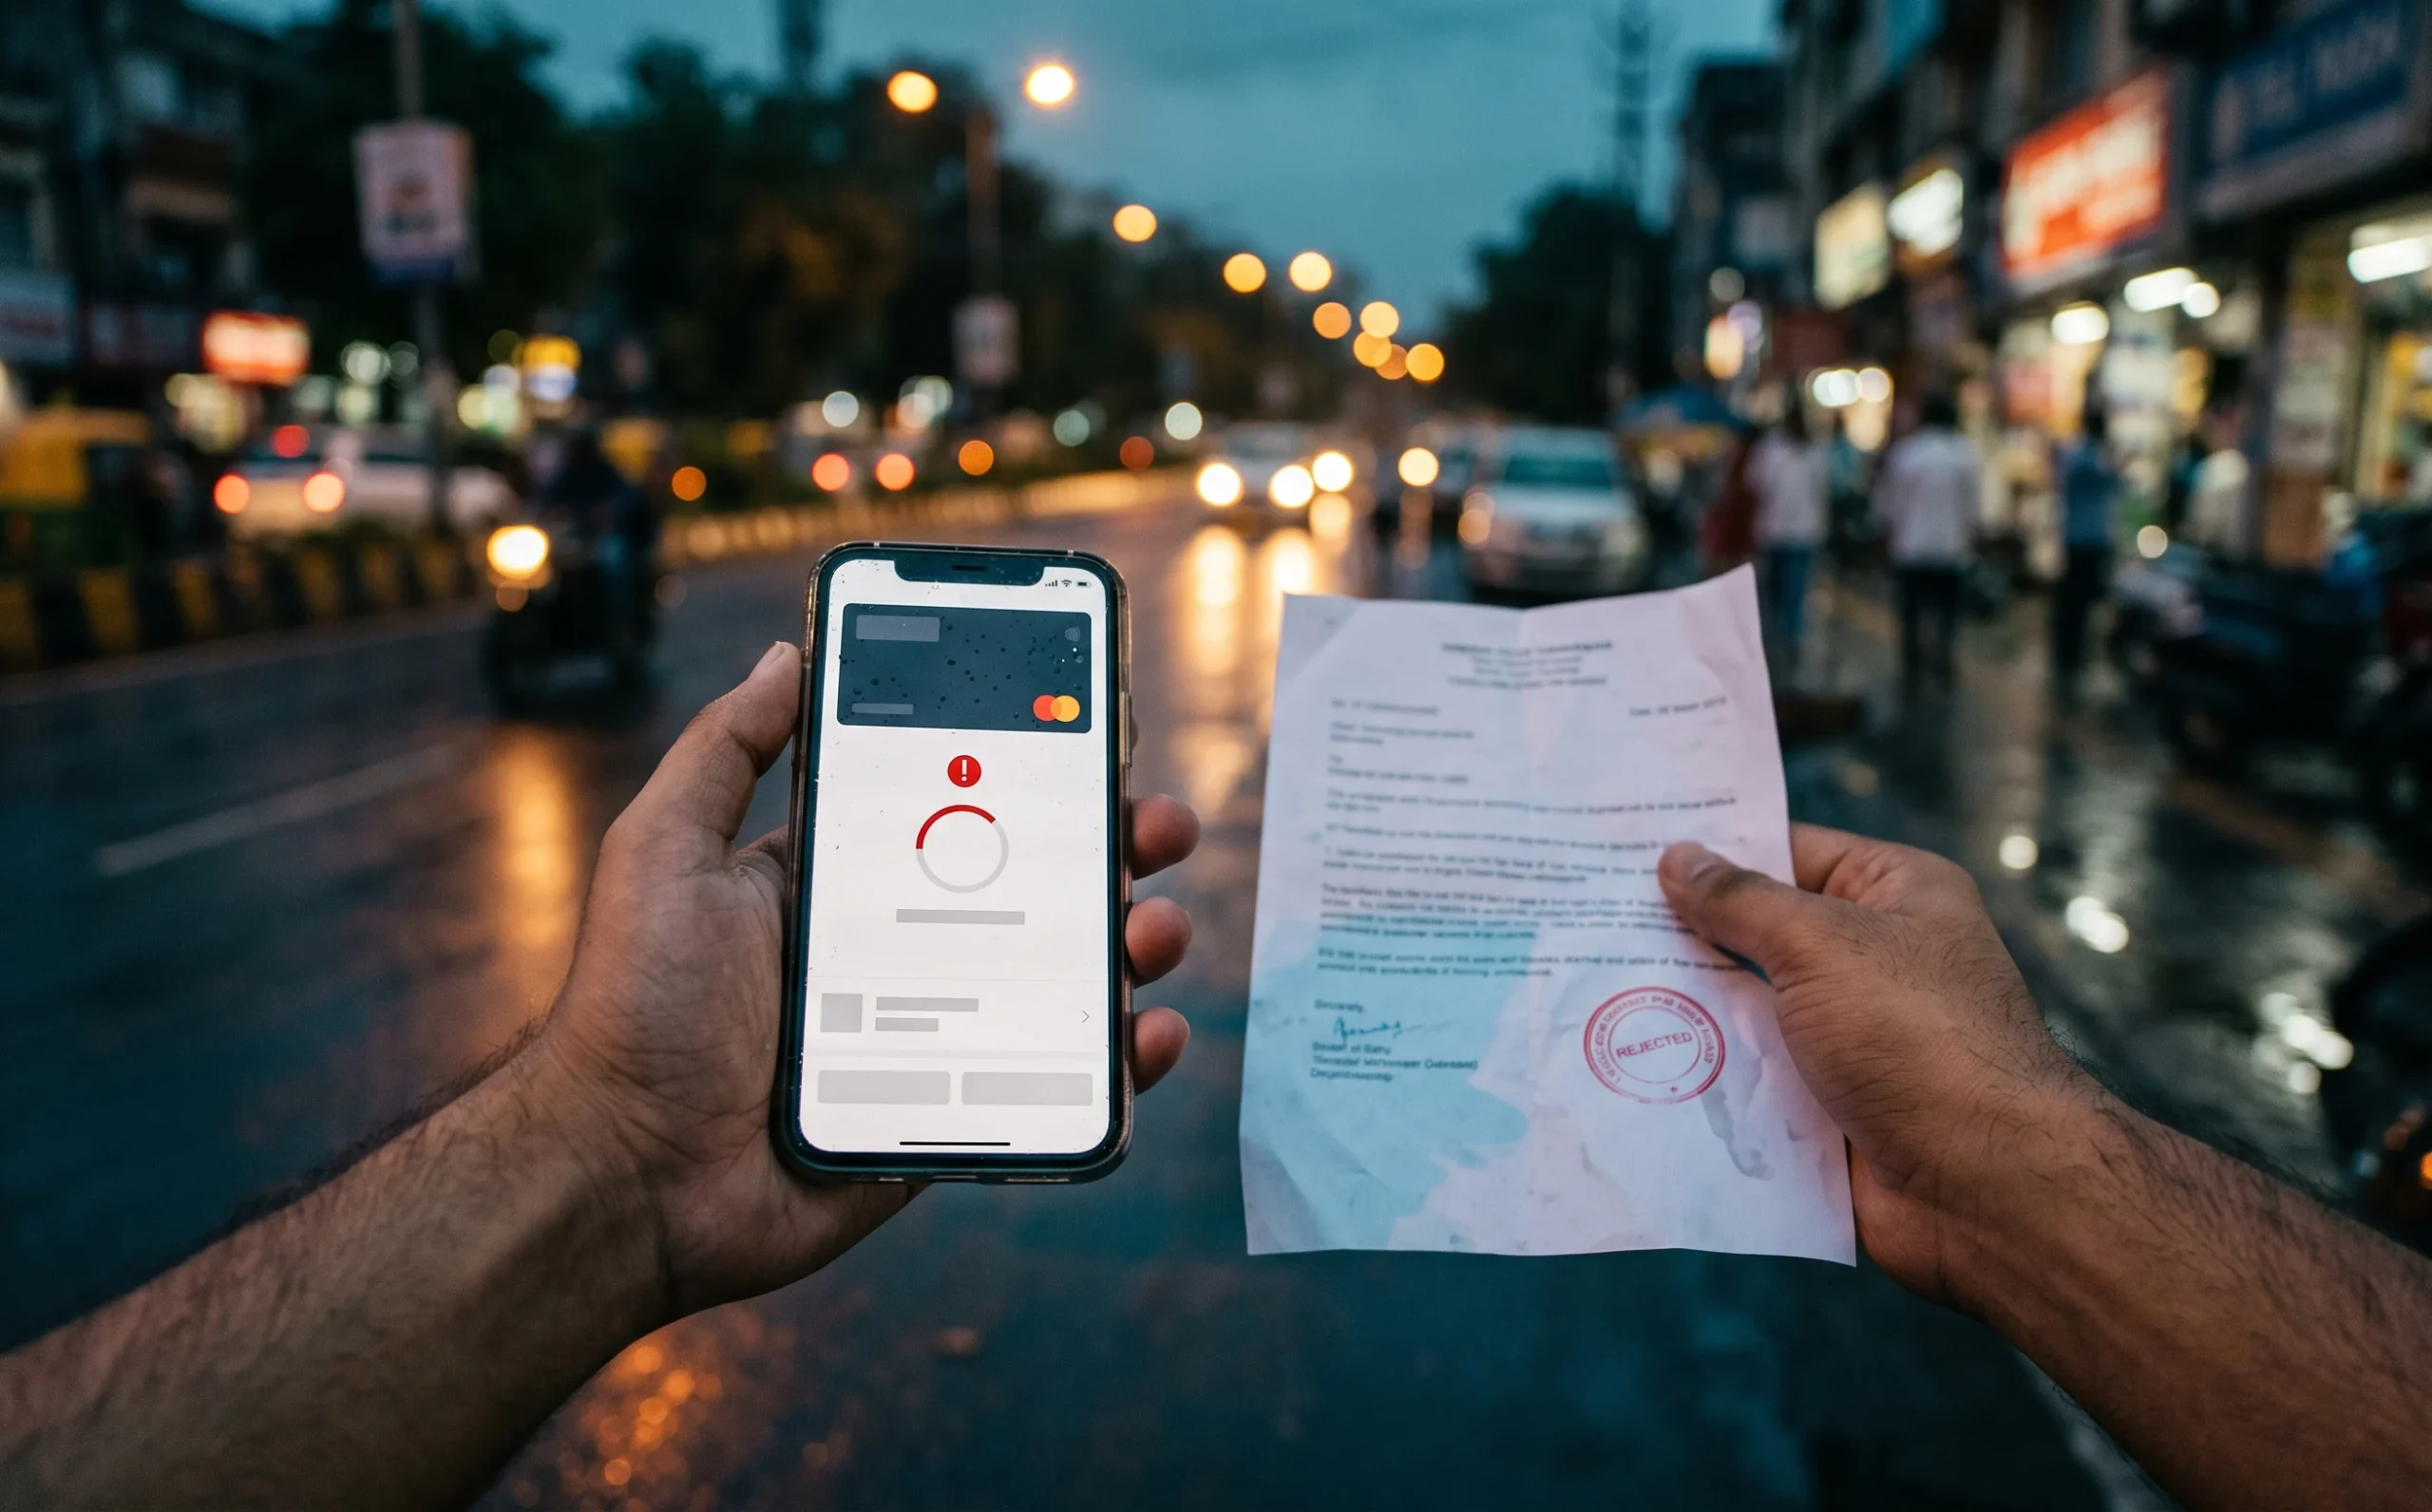
The primary financial services UX challenges stem from digital stagnation. Banks have achieved feature parity—instant transfers, chatbots, and card freezes—but underlying experience architectures remain outdated. Customers abandon platforms not because of bad screens, but due to unexplained blocks or rejected documents originating deep within risk engines. With Generative AI adoption in banking projected to jump from 5% to over 80% by 2026, interfaces must evolve rapidly.
How Can Systemic UX Align Compliance with Customer Experience?
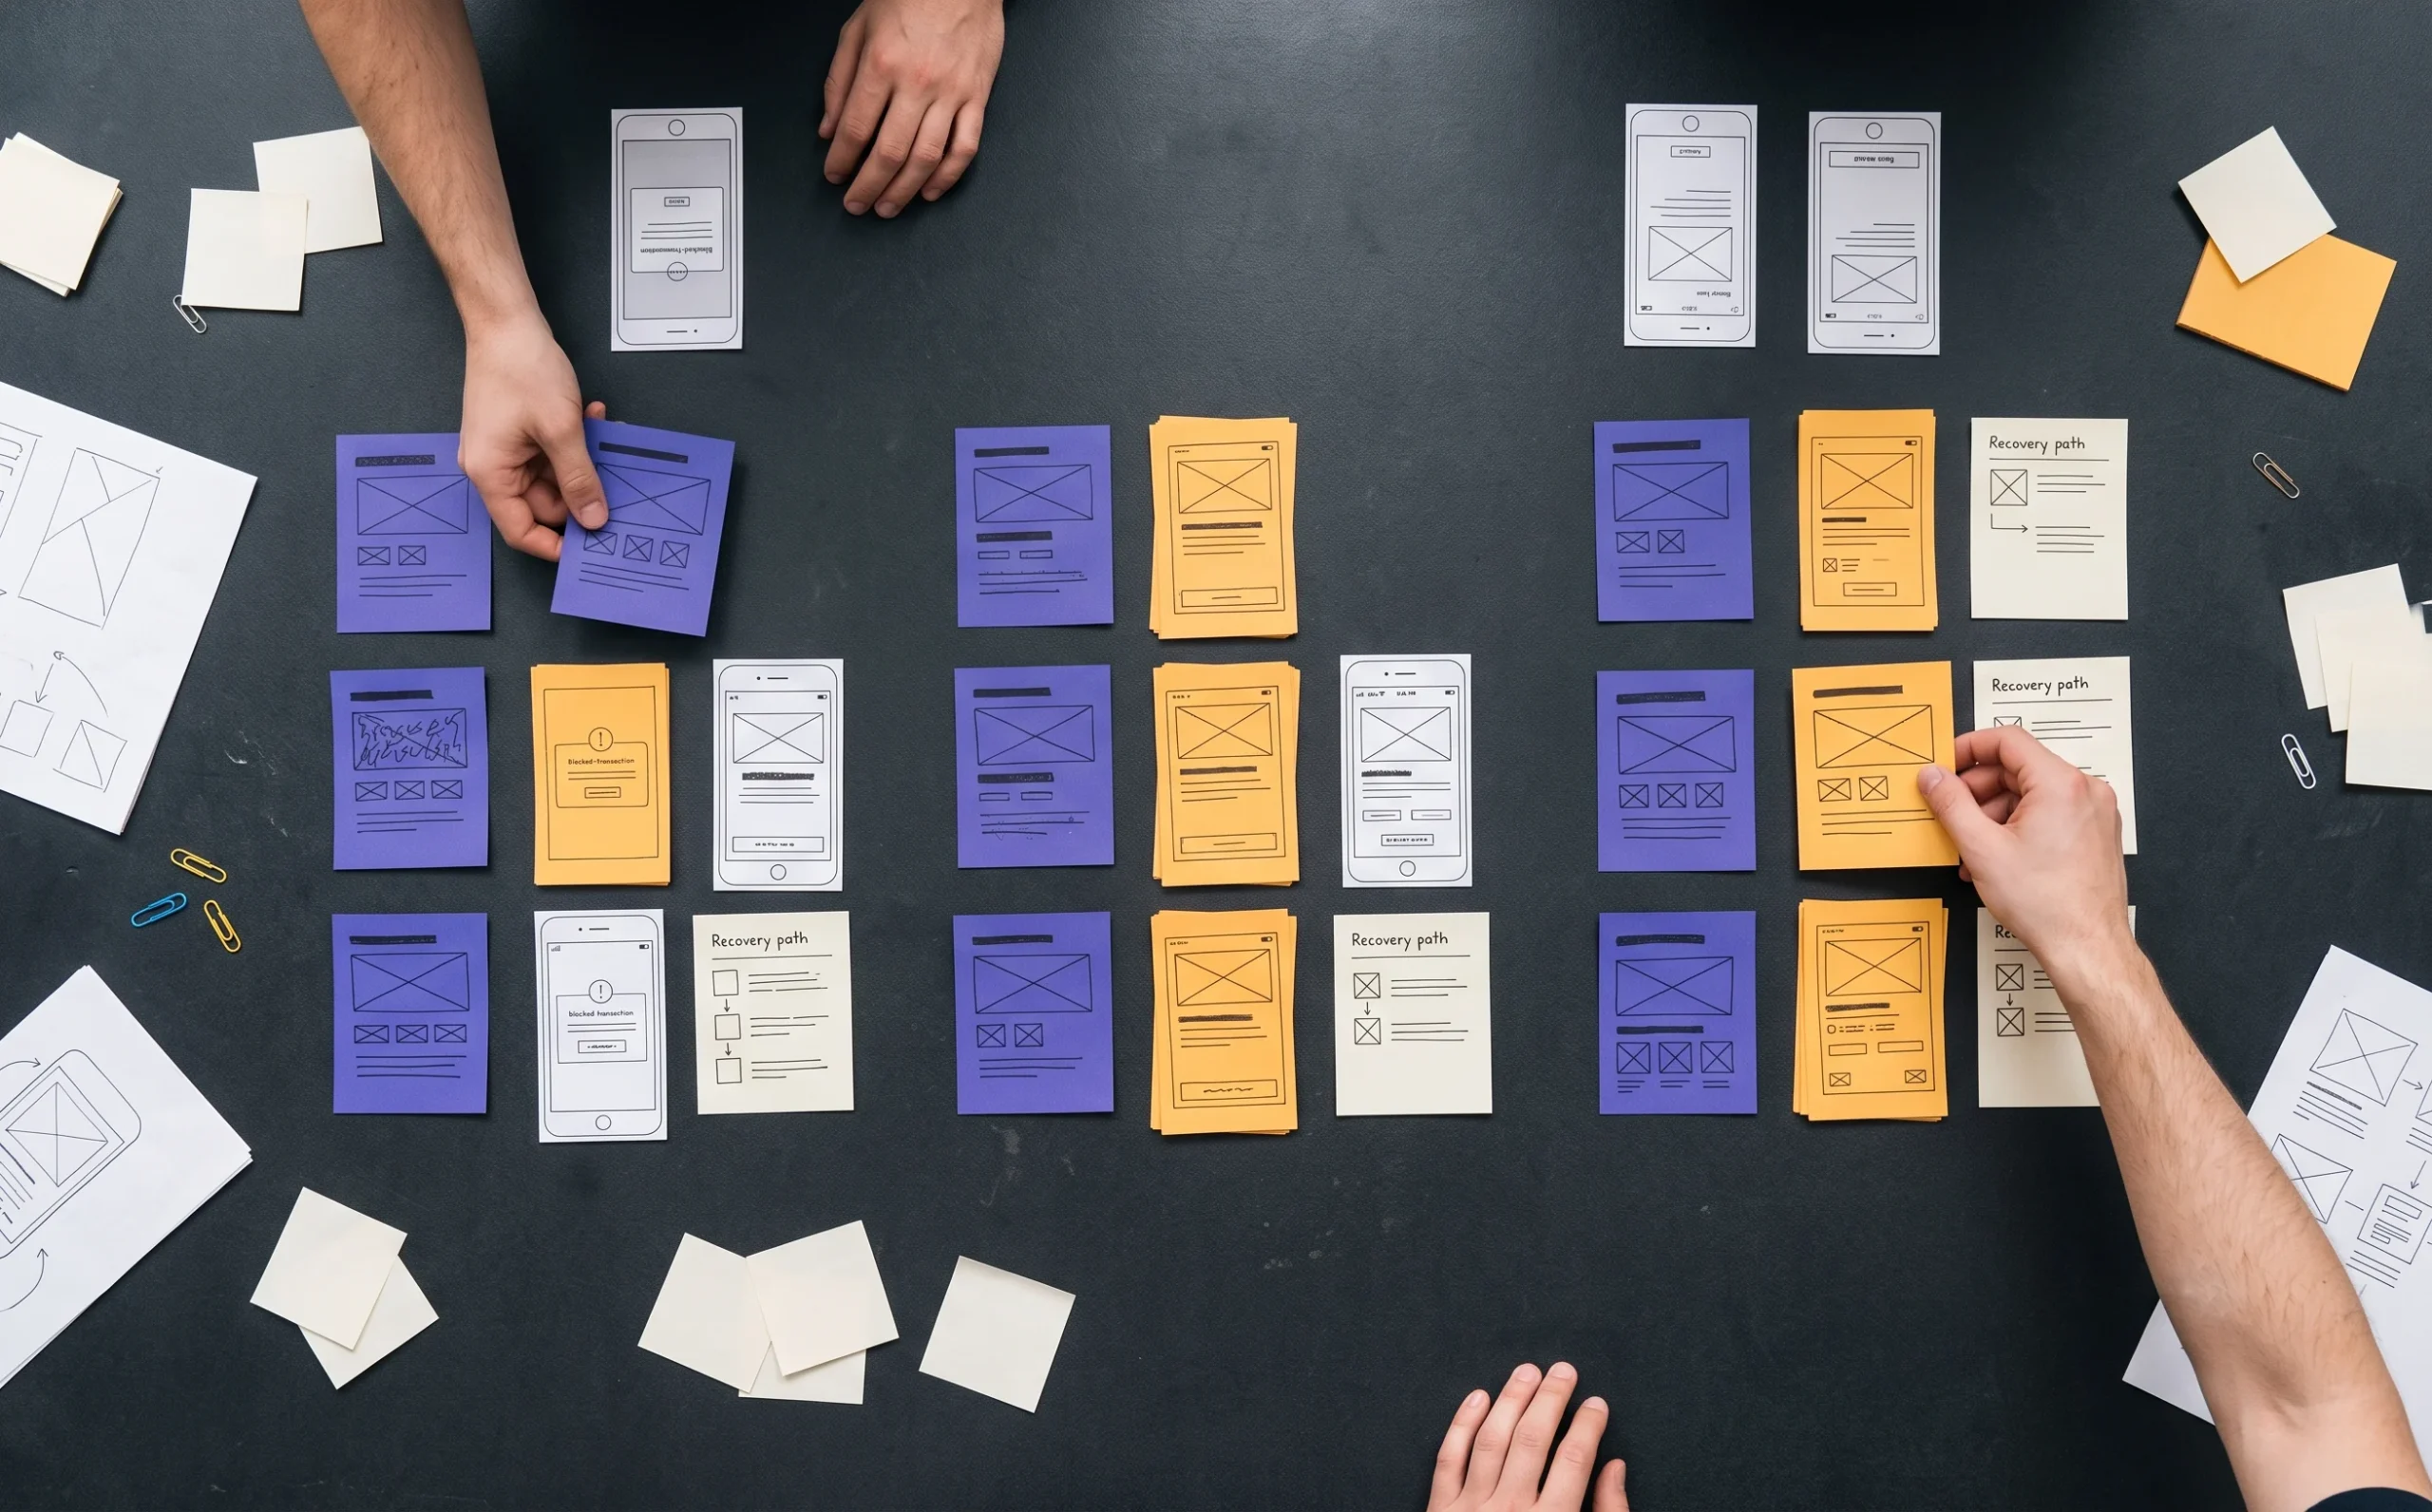
Systemic UX in finance aligns compliance and experience by designing risk models and interfaces simultaneously. Key pillars include:
- Shared decision architecture: Defining interface consequences for every automated rule.
- Explainability at interruption: Communicating the specific reason a transaction is blocked.
- Resolution paths: Designing clear recovery paths for exception states, which determine retention.
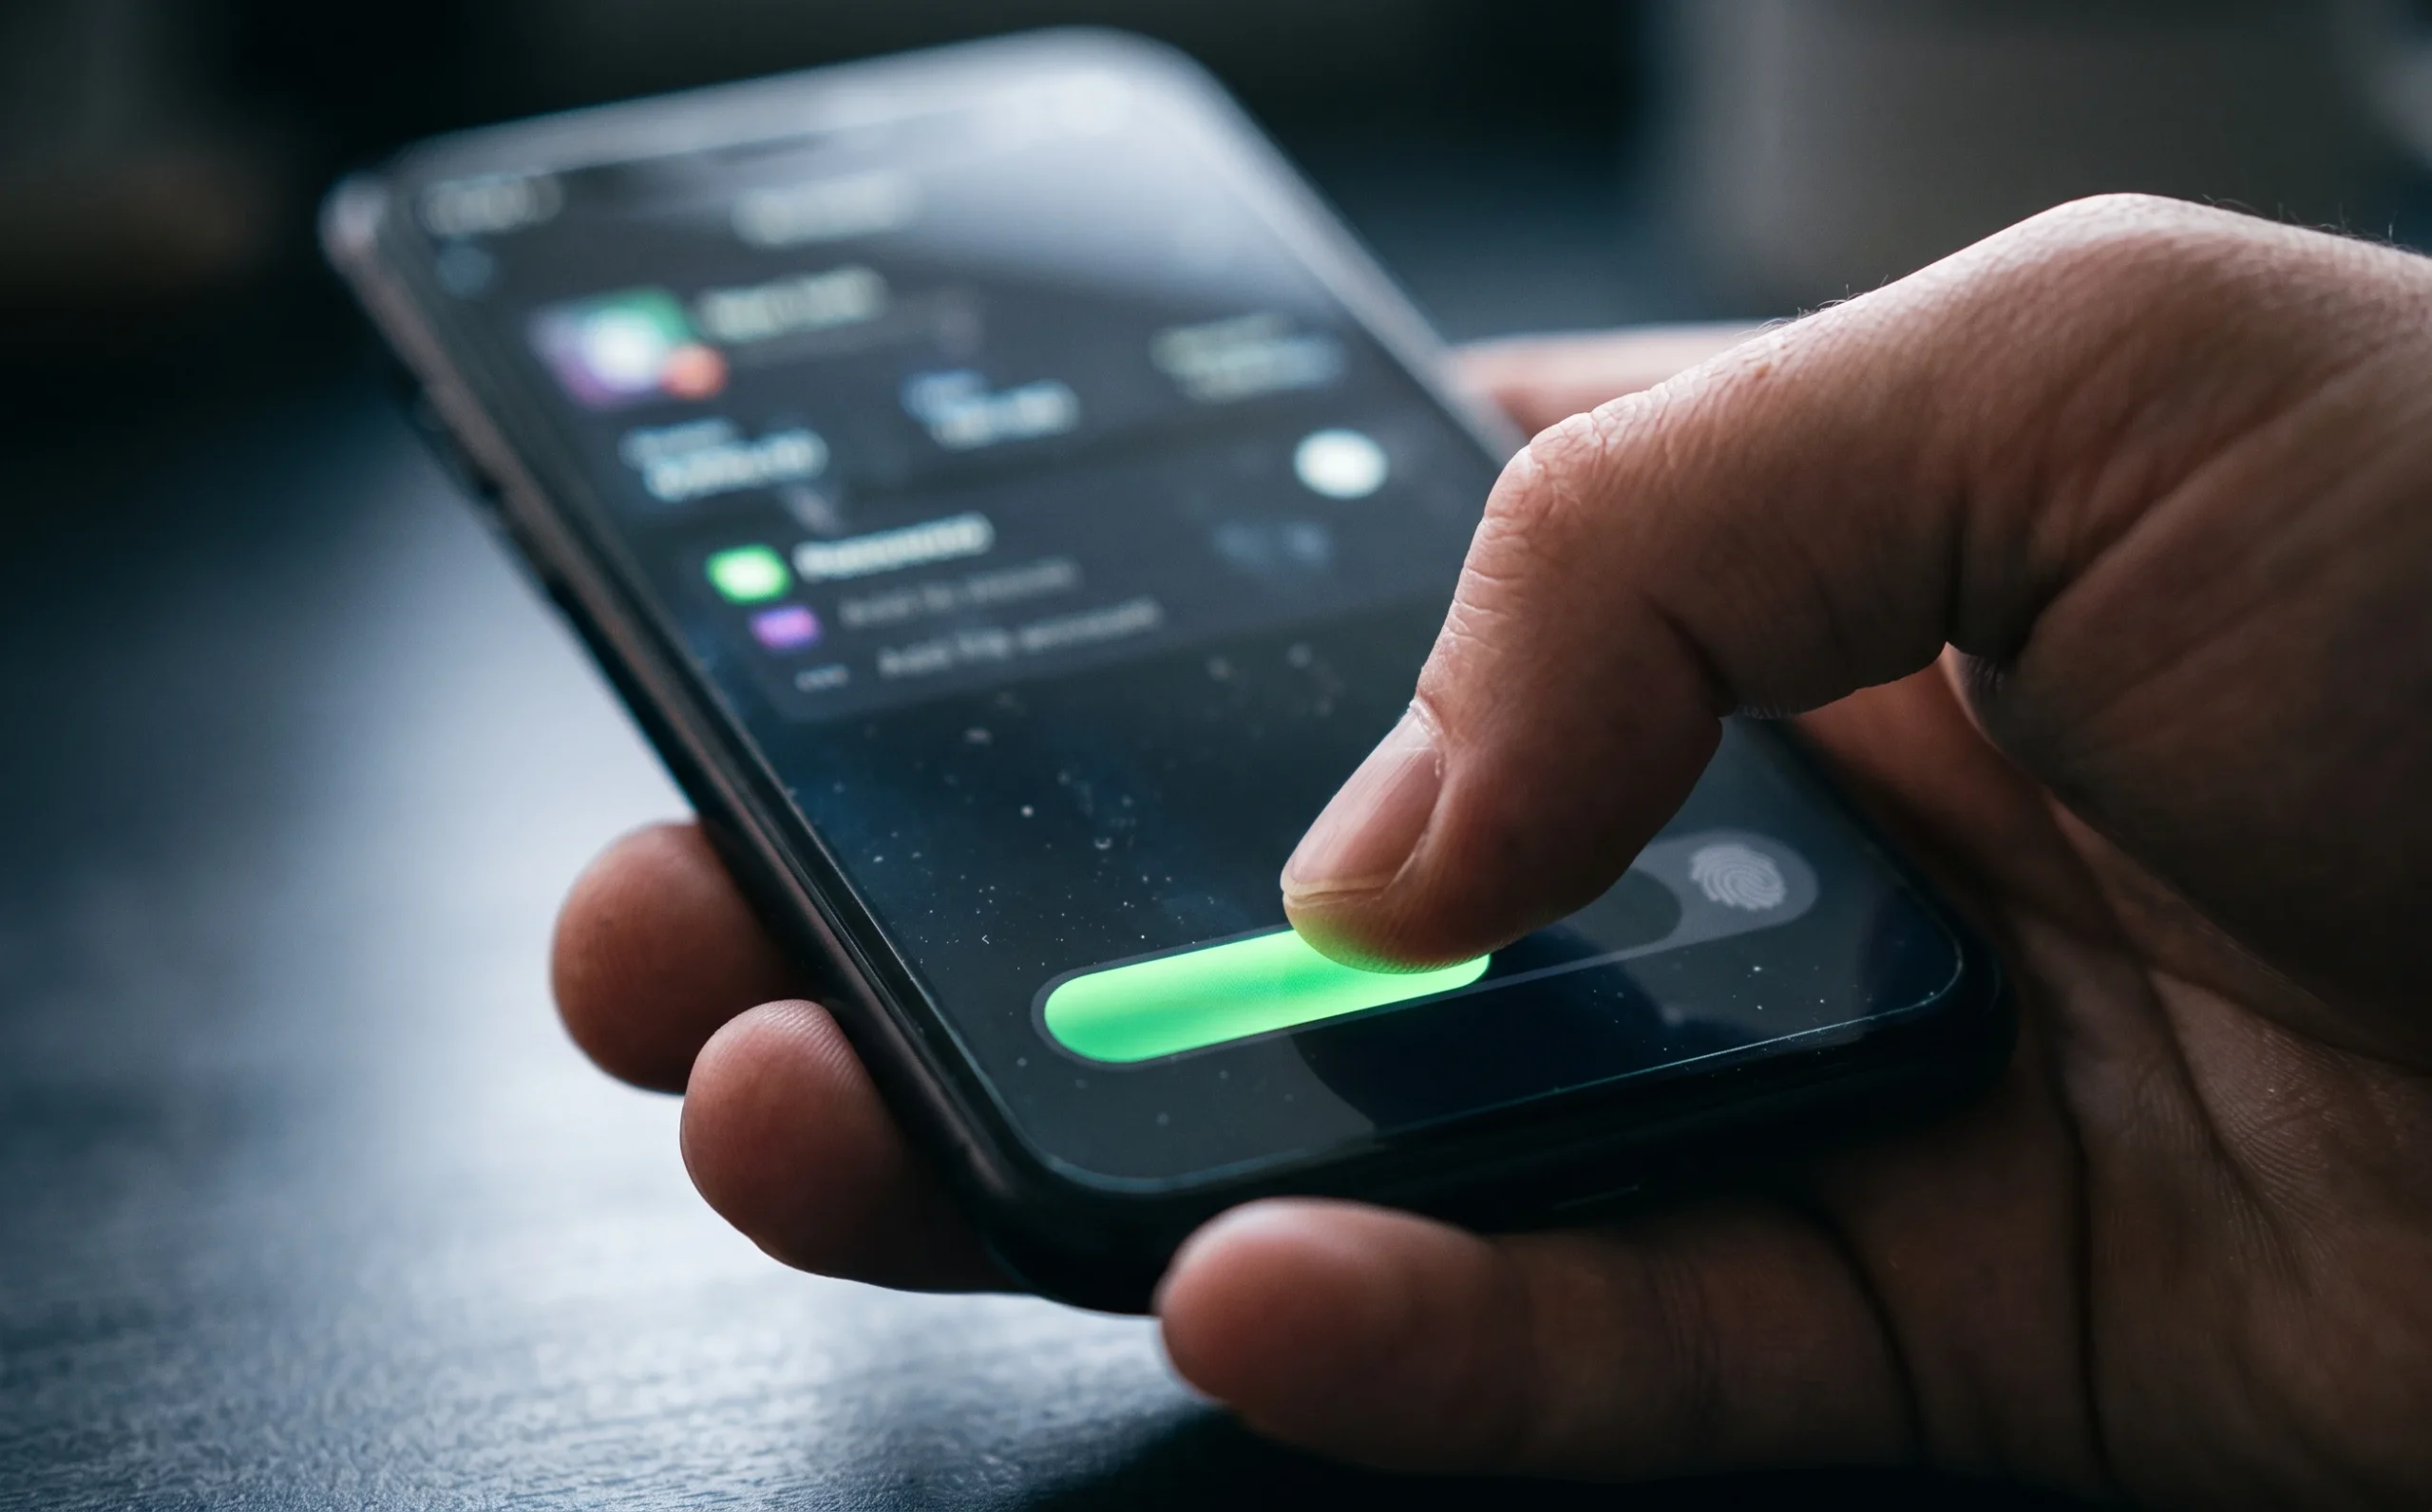
What is the Smart Friction Framework?
The smart friction framework separates harmful friction from trust-building friction. While ‘frictionless’ design is a common goal, high-stakes financial transfers require psychological signals that a consequential action is happening. Smart friction—like a slide-to-confirm gesture or a biometric prompt—makes deliberateness visible, reassuring users that the system is secure and paying attention.
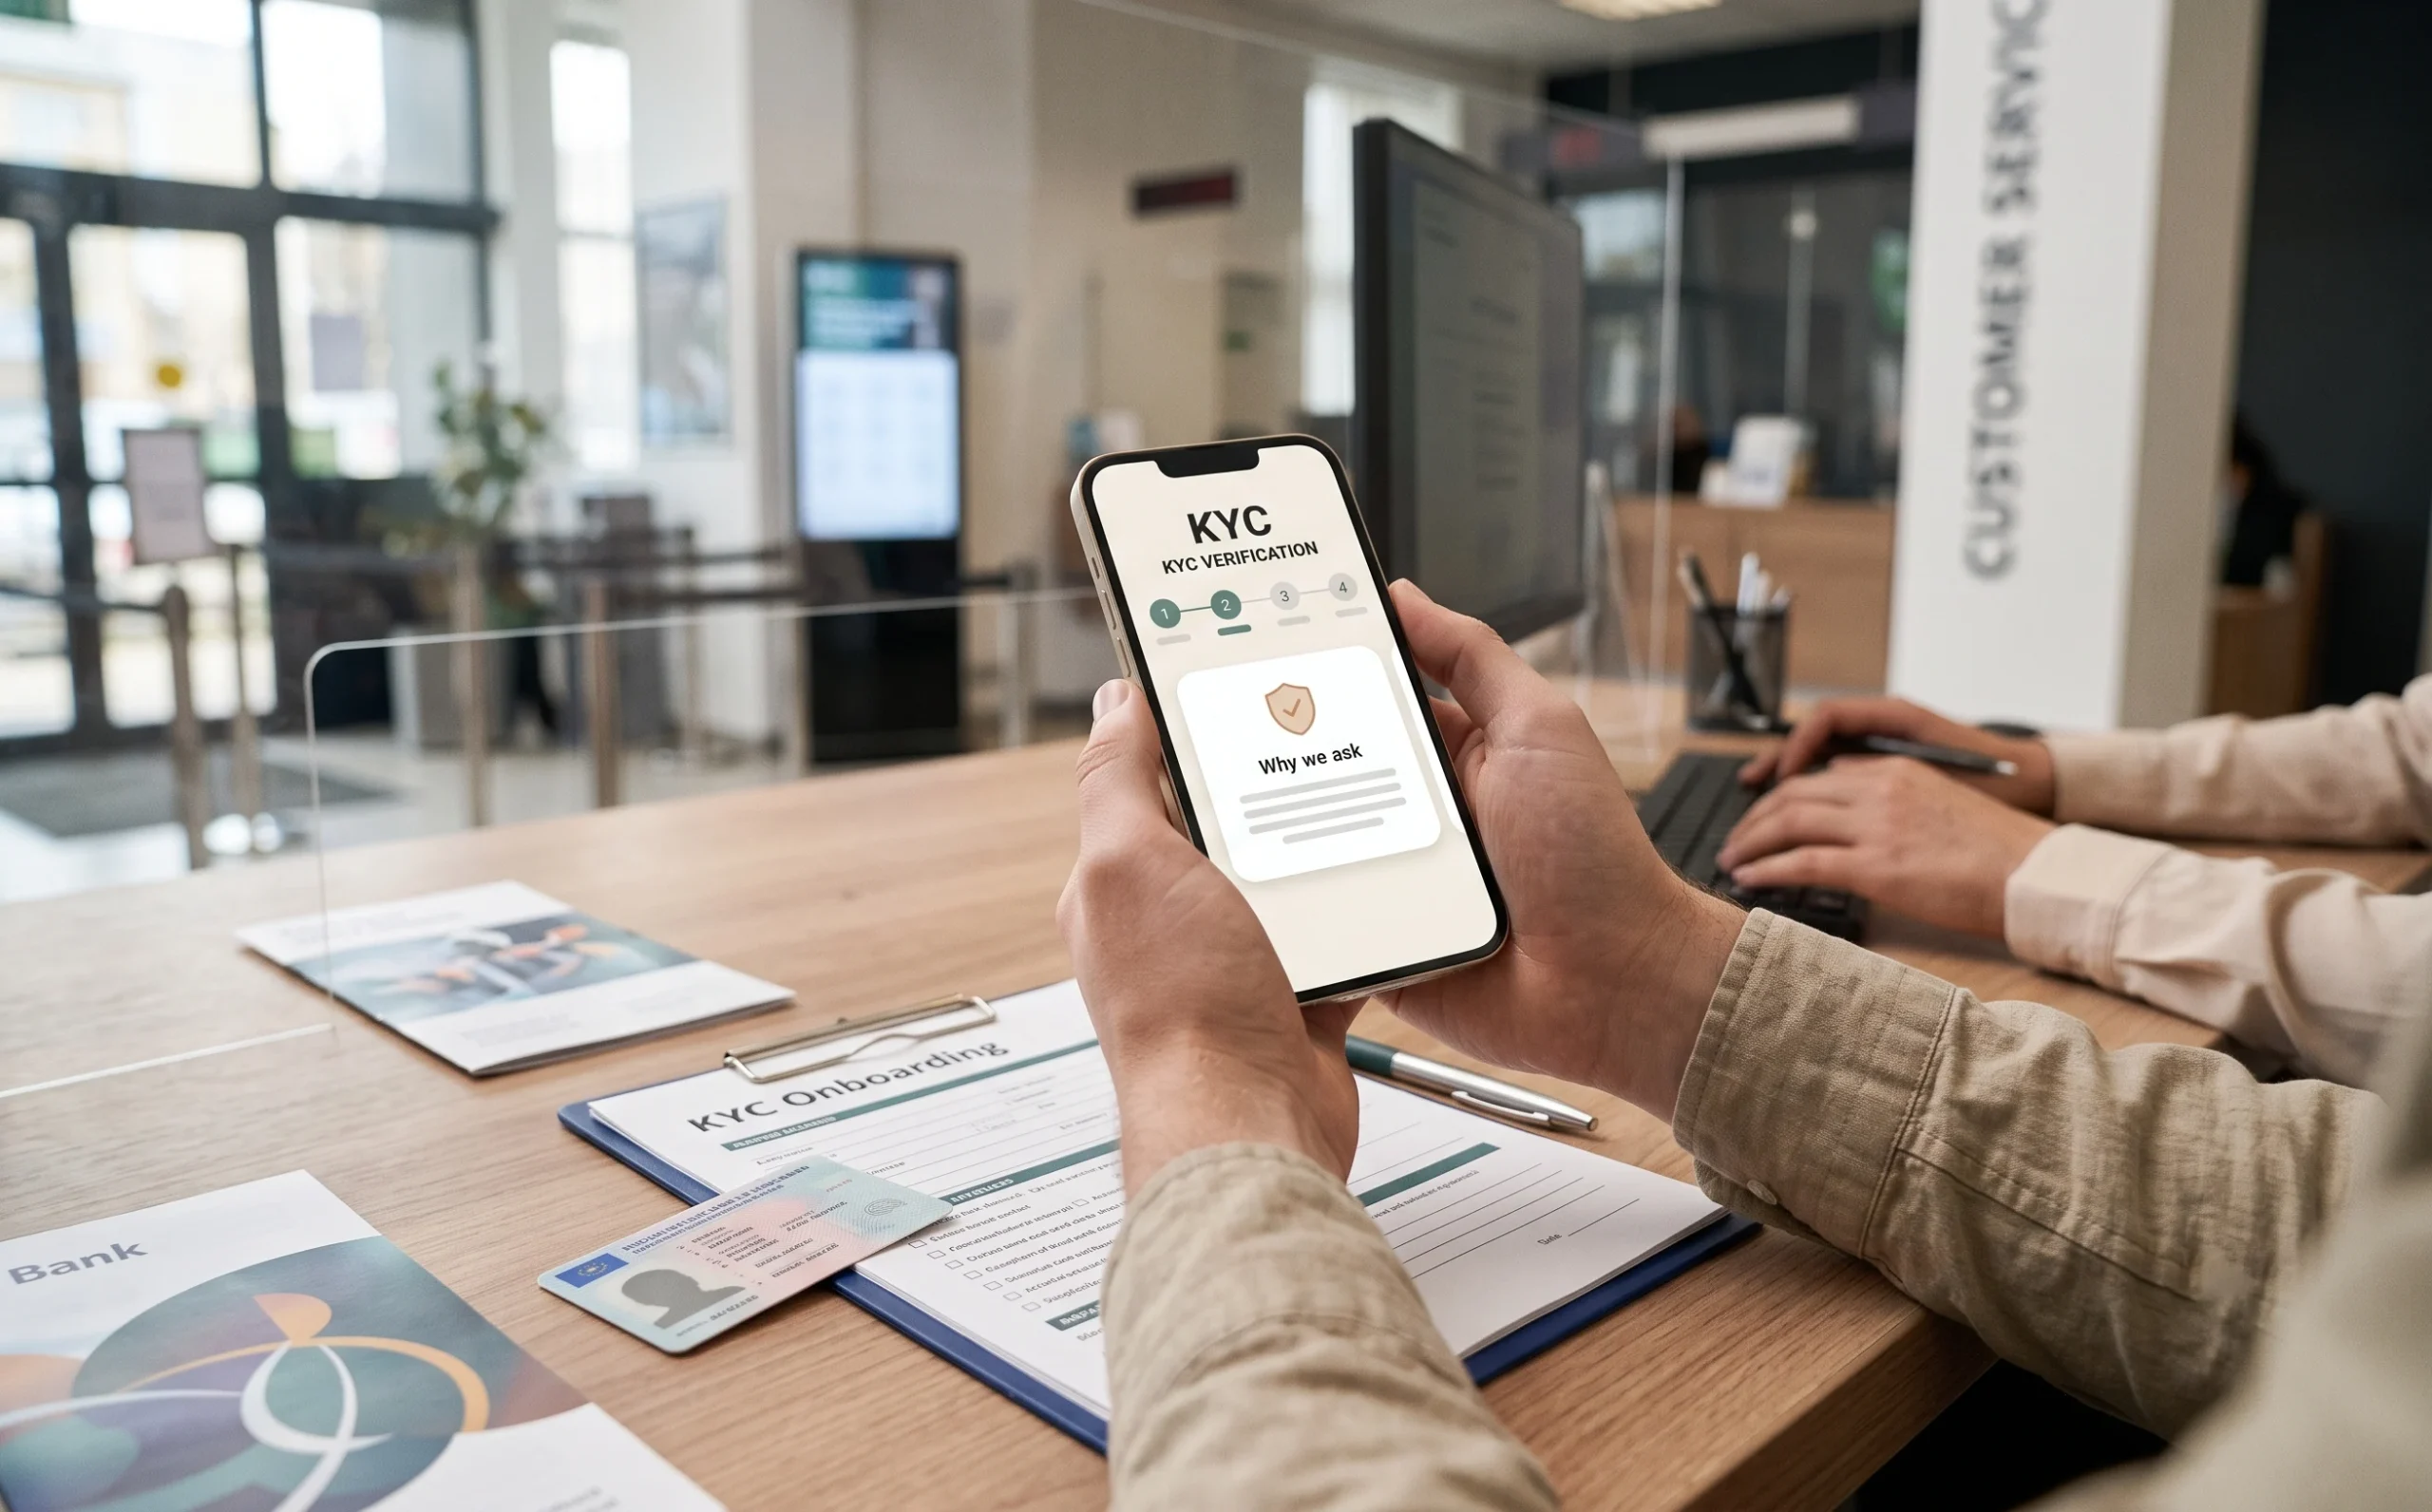
How Can Banks Humanize KYC and Transform Compliance?
Humanizing KYC transforms mandatory verification into a brand-building interaction. Replace legalistic phrasing with plain-language explanations of why data is needed (e.g., preventing account takeover). Provide real-time progress states and honest wait timeframes during manual reviews. This transparency reduces onboarding drop-offs without compromising controls.
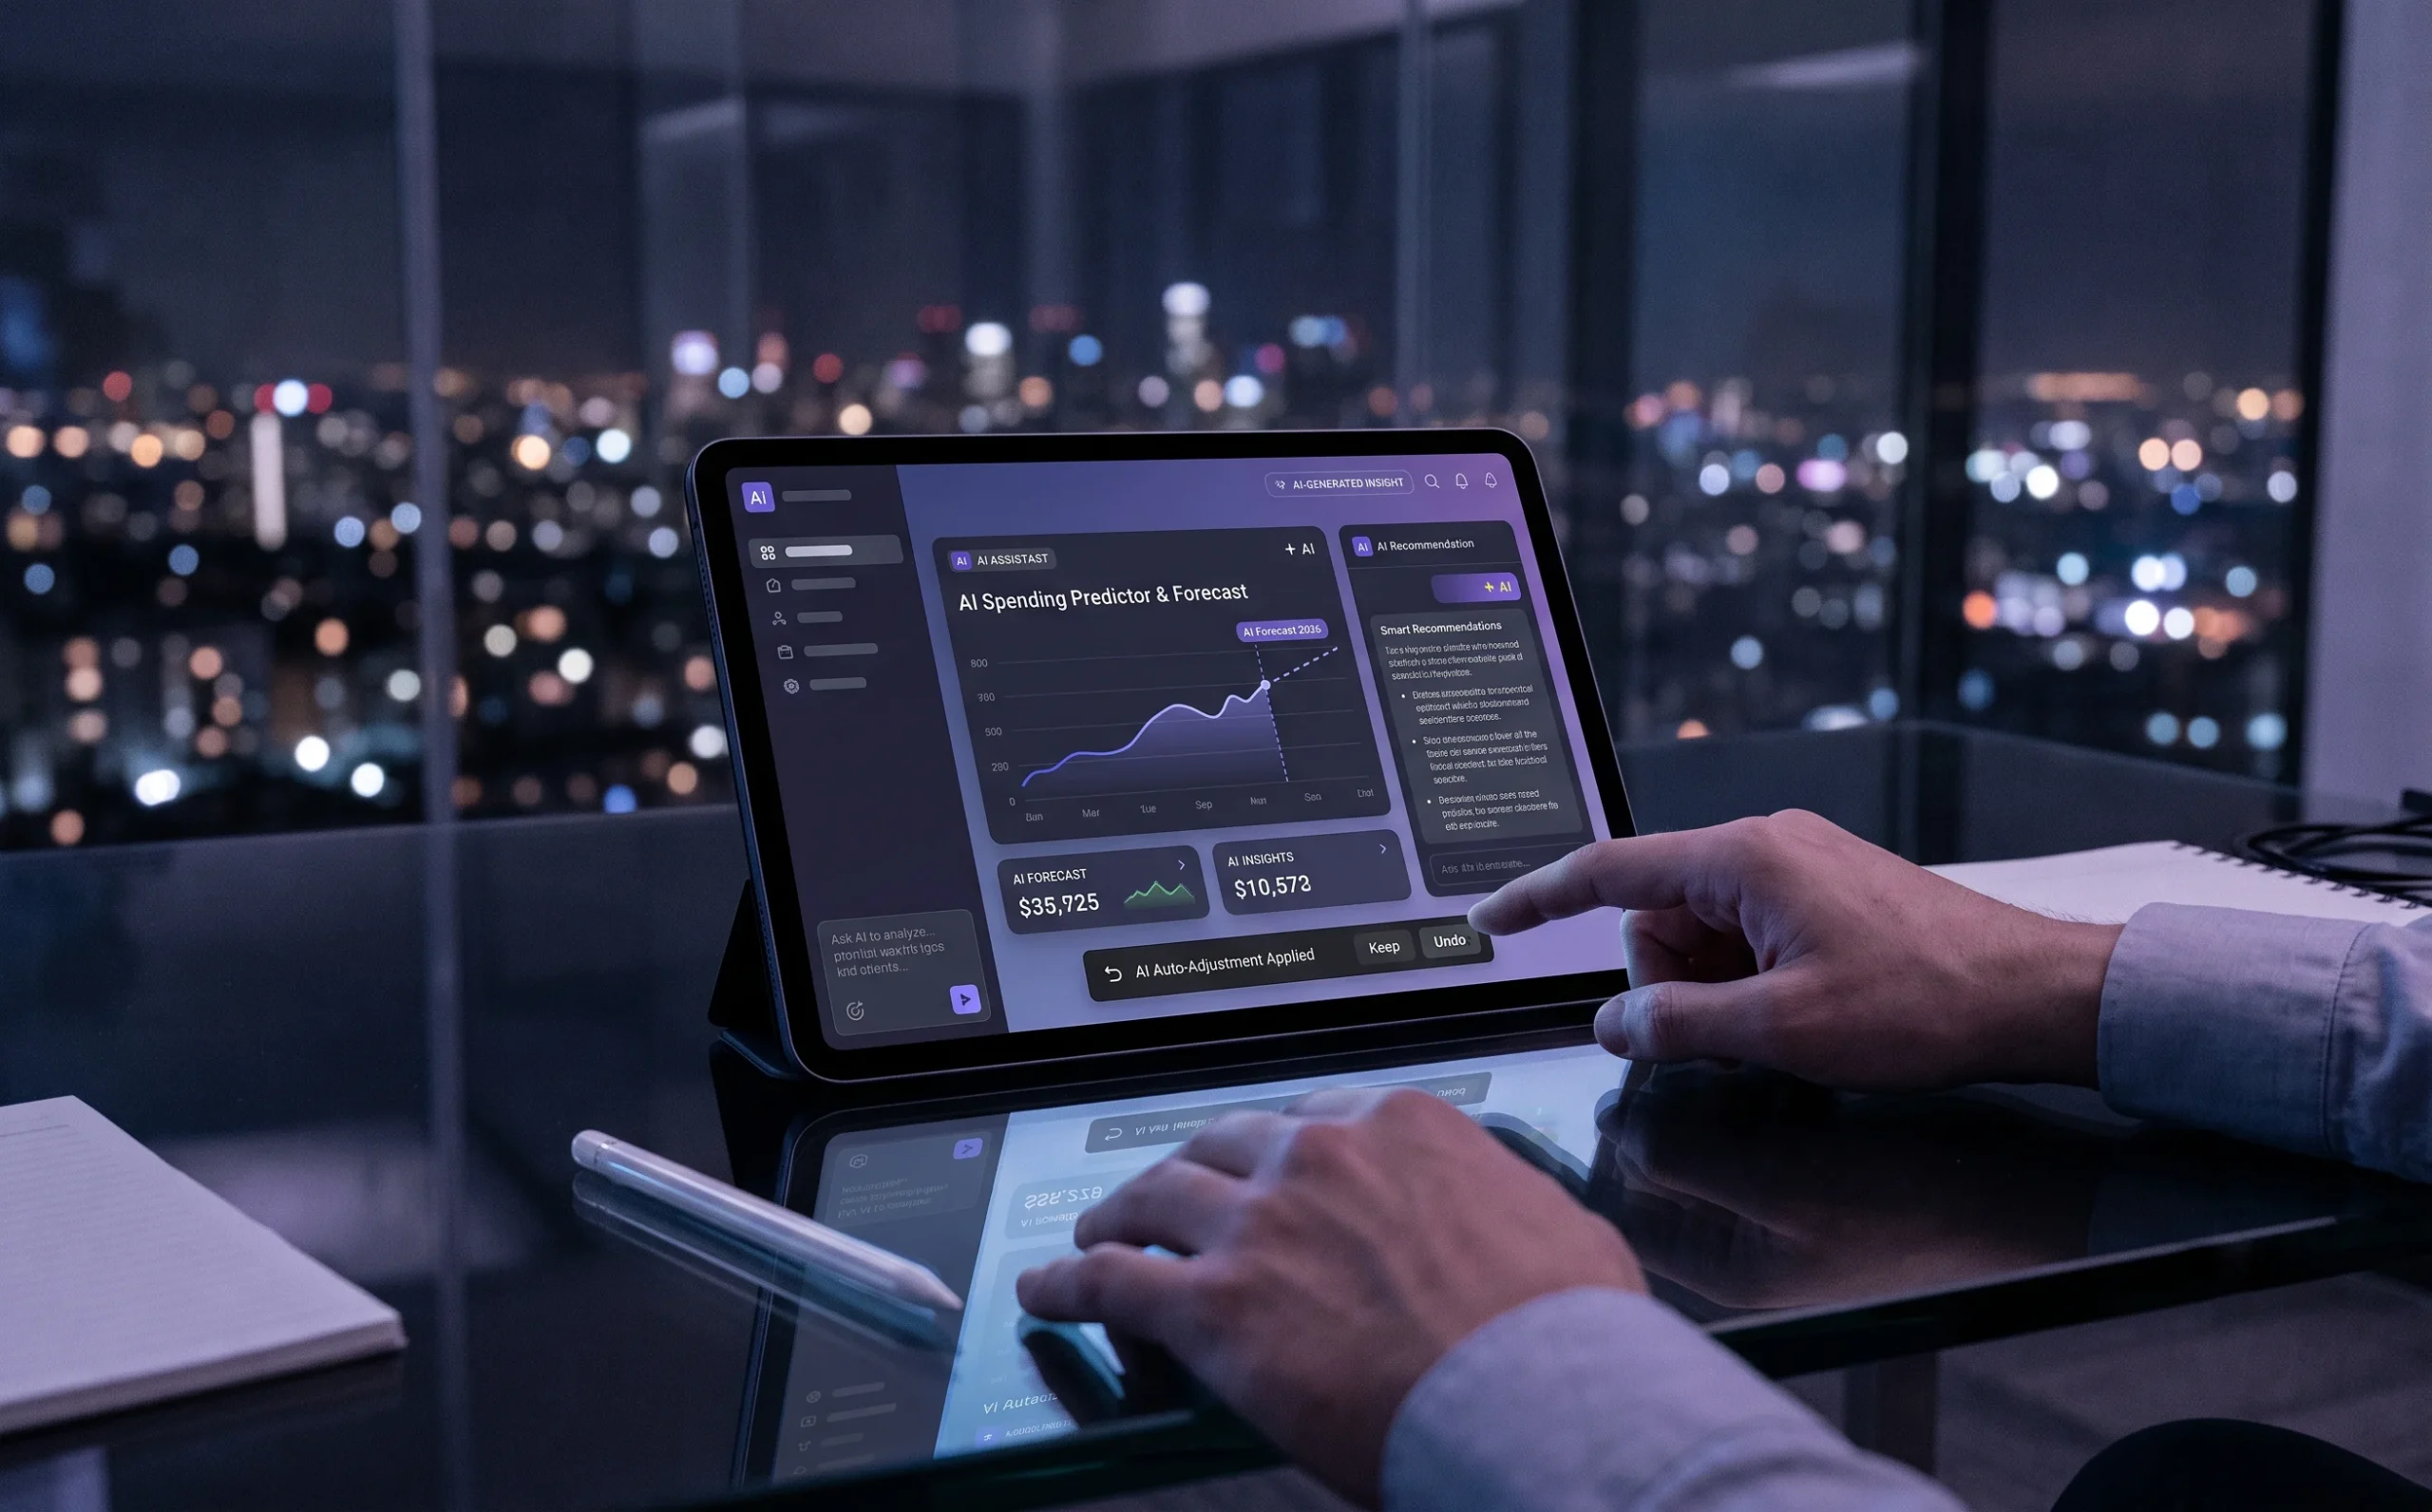
How Should You Design for the AI-Driven Future in 2026?
As AI handles more financial decisions, UX must focus on provenance and reversibility. AI-generated insights must show their basis to avoid reading like sales pitches. Automated actions require clear undo options. In a robust BFSI digital transformation strategy, the interface layer must match AI capability with uncompromised user comprehension.
Frequently Asked Questions
What are the biggest financial services UX challenges?
The biggest challenges involve translating complex back-end risk and compliance decisions into clear, manageable user interfaces without causing transaction abandonment.
What is the smart friction framework?
It is a design strategy that intentionally introduces minor delays or confirmation steps during high-stakes actions to increase user confidence and prevent errors.
How does humanizing KYC improve conversion?
By explaining the regulatory ‘why’ behind data requests in plain language, users feel protected rather than suspected, dramatically reducing onboarding abandonment.
What is a BFSI digital transformation strategy?
It is a comprehensive plan to modernize banking, financial services, and insurance operations, prioritizing user adoption, systemic UX, and AI integration over mere feature delivery.
Written by Team ScreenRoot. 16+ years leading enterprise UI/UX research for BFSI, SaaS, and Healthcare clients.
When you’re ready, let’s talk.
📞 Call us (Toll-Free): 1800 121 5955 (India)
✉️ Email us: [email protected]