1800 121 5955
Key Takeaways
- Only 29% of leading mobile apps achieve a decent UX performance rating, meaning a frictionless fintech app onboarding flow is a durable competitive moat rather than table stakes.
- Define activation around one 24-hour ‘Aha moment’—a linked account, a pre-approved limit, or a first transfer—and delete every non-regulatory field standing in front of it.
- Use progressive profiling to separate non-negotiable KYC hard requirements from soft segmentation data, triggering verification when the user initiates a high-value action.
- Deploy real-time client-side camera validation (blur, glare, and four-corner edge detection) with prescriptive microcopy to eliminate server-side ID document rejections.
- Persist signup state at the individual field level on the server and combine deep-linked push notifications, email bridging, and chatbot assistance (already used by 37% of U.S. consumers) to recover interrupted sessions.
Fintech app onboarding is the structured sequence that guides a new user from initial app install through identity verification (KYC) to their first completed financial action. Most financial app onboarding flows underperform because the teams optimizing them have never agreed on the finish line—so product, marketing, and legal stakeholders each add one more field to the signup form and nobody removes anything.
The bar for differentiation through UX is surprisingly low. Only 29% of leading mobile apps achieve a decent UX performance rating, and across developing digital economies, UI/UX flaws are consistently identified as the single most significant quality issue in fintech applications. At the same time, regulatory complexity is rising—applications for fintech innovation and regulatory sandbox support increased by 49% in 2023—while consumer readiness for automated guidance has matured, with 37% of the U.S. population interacting with bank chatbots.
ScreenRoot simplifies complex regulated journeys for global financial brands by fixing the destination before rebuilding the road. Here are the six proven steps to improve fintech UX, reduce KYC abandonment, and drive measurable 24-hour activation in 2026.
Step 1: How do you map your fintech ‘Aha Moment’ matrix?
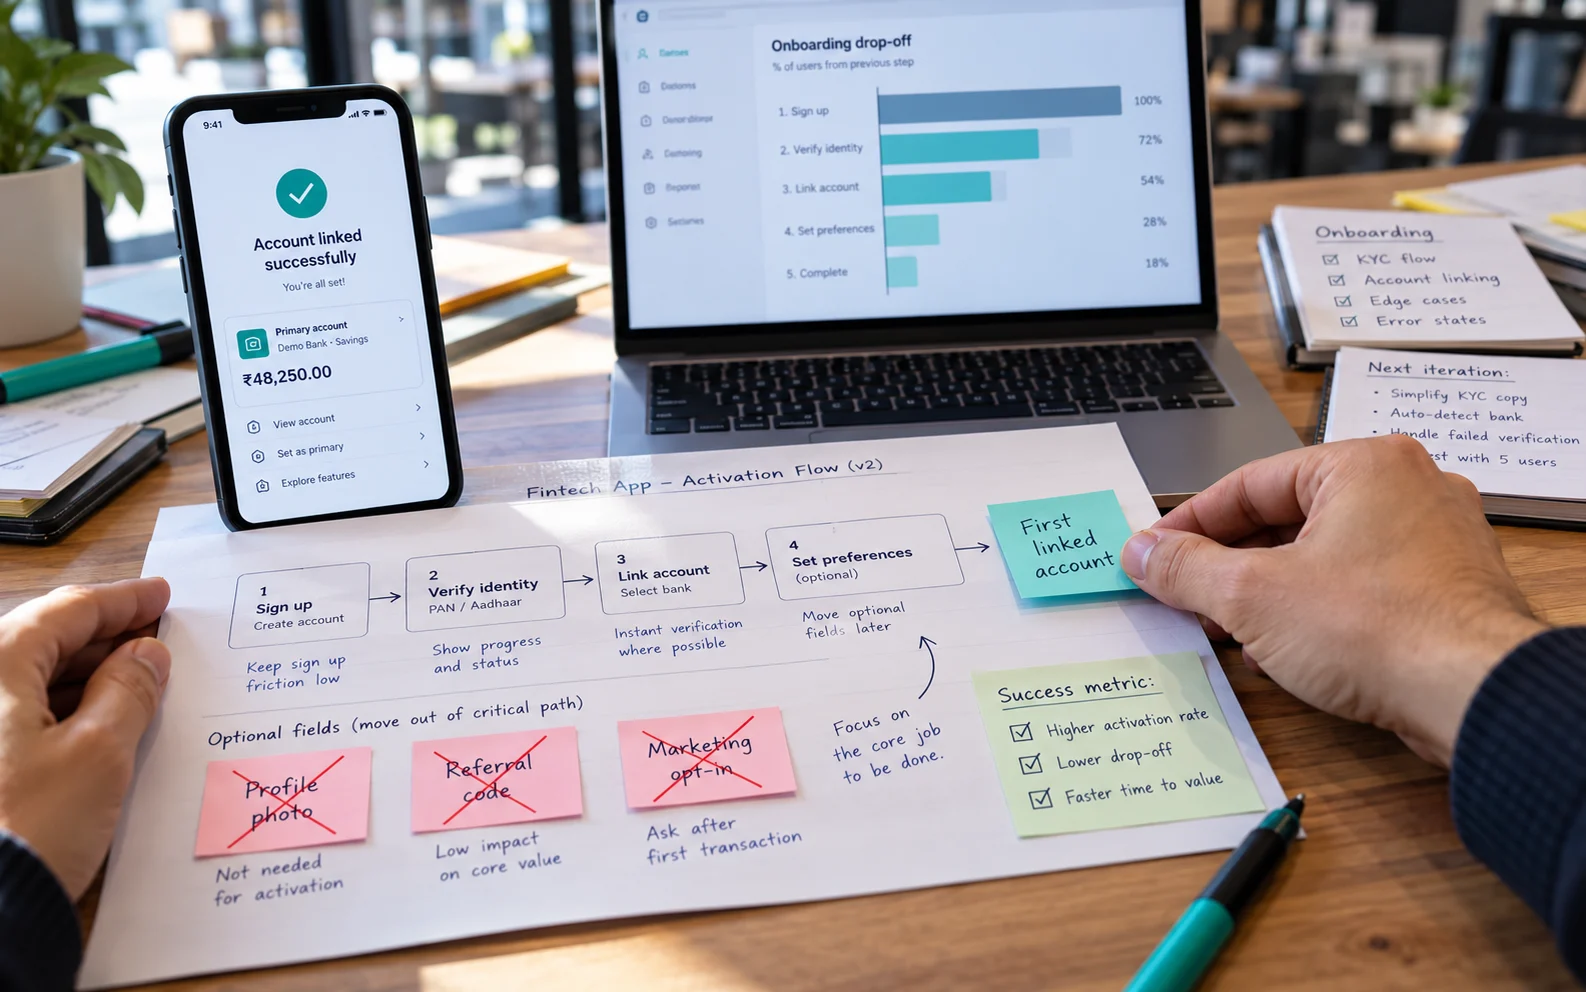
Map your fintech ‘Aha Moment’ matrix by defining what ‘activated’ actually means for your product and stripping out every tap, field, and permission dialog that does not serve that moment or a regulator. Build your activation matrix in four disciplined moves:
- Name the single action that proves value. For wealthtech, that is the first linked external account. For lending, it is a pre-approved credit limit appearing on screen. For payments, it is the first successful transfer, however small.
- Audit the current path to that action. Count every tap, form field, and OS permission dialog between app open and the moment of value. Most product teams are surprised by the total.
- Delete anything that does not serve the moment or a regulator. Marketing preference checkboxes, optional profile photos, and referral code fields belong later. Everything you cut is friction you no longer have to design around.
- Agree on one 24-hour success metric across product and growth. Measure the percentage of new users reaching the named value action within the first day—not raw downloads or unverified account creations.
Step 2: How do you implement progressive profiling for KYC?
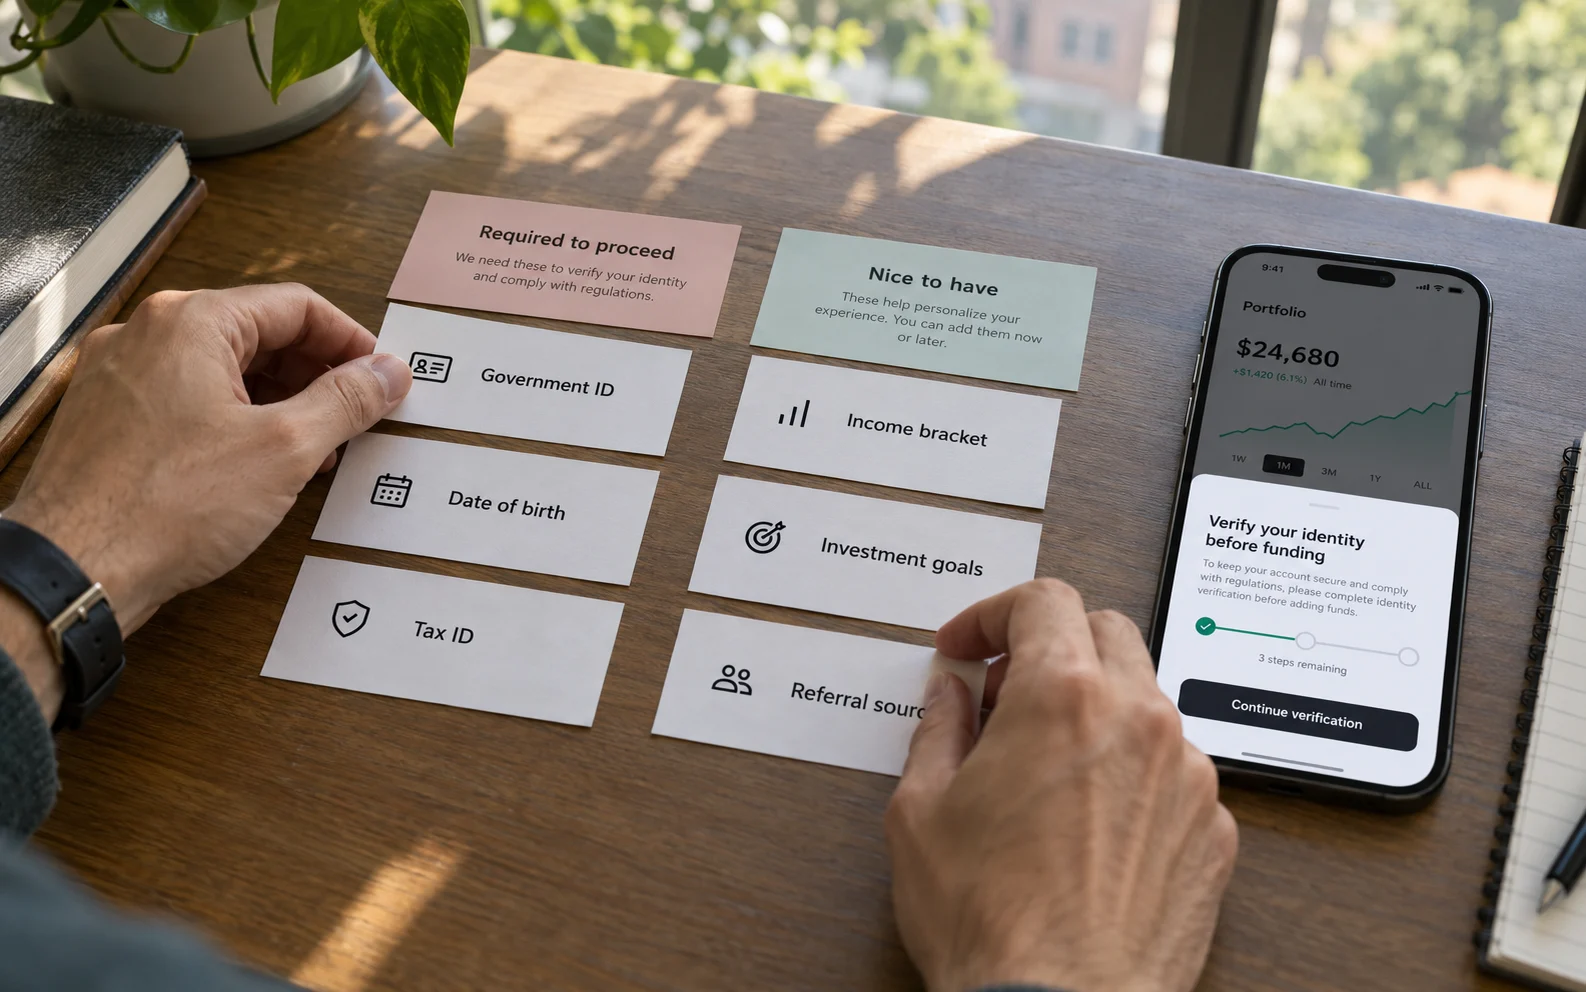
Implement progressive profiling by sorting every data field into hard regulatory requirements versus soft product-segmentation requests, then tying each hard KYC request to the exact moment the user initiates a high-value financial action. Treat hard and soft requirements identically upfront and you will build a wall where you needed a door.
| Hard Requirements (Non-Negotiable Regulatory Floor) | Soft Requirements (Defer In-Session Post-Activation) |
| Legal name and date of birth | Employment details and job title |
| Government ID verification | Annual income bracket |
| Proof of address (where mandated) | Investment goals or risk appetite |
| Sanctions and PEP screening | Marketing channel attribution |
| Tax identification for funded accounts | Referral source and communication preferences |
Hard requirements are non-negotiable; the question is never whether to collect them, only when. Let users into the product with an email and passcode first so they can explore a dashboard, demo portfolio, or rate calculator. Exploration builds the motivation that carries someone through verification later. Trigger KYC at the first high-value action (funding an account, requesting credit, or initiating a transfer), deep-link directly to the specific outstanding requirement, collect soft data later when the user is browsing relevant products, and always show a real progress indicator—three steps remaining is tolerable; an unmarked corridor is not.
Step 3: How does real-time camera feedback prevent document capture drop-off?
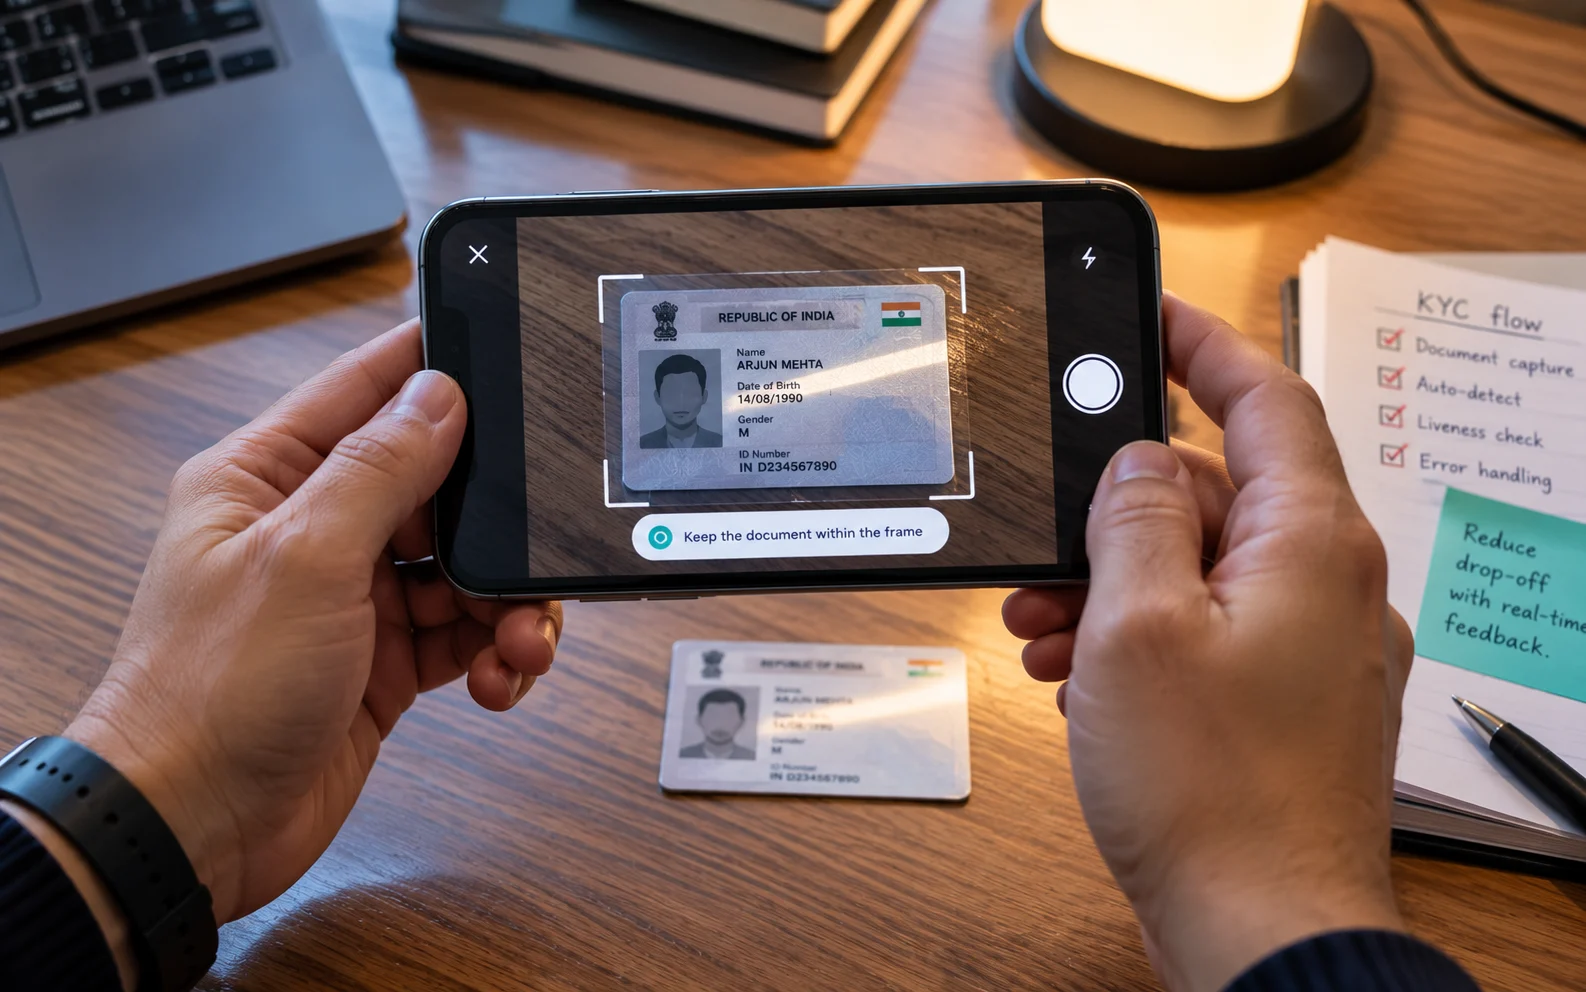
Real-time camera feedback prevents document capture drop-off by evaluating blur, glare, and four-corner framing at the camera layer before the shutter fires, ensuring the user is never allowed to submit an ID image that will fail server-side review. If a user opens their wallet, photographs their ID in poor lighting, and receives a server rejection thirty seconds later, you have lost them.
Prevention is far cheaper than recovery. Integrate inline computer-vision validation at capture and replace generic failure messages (‘Upload failed, please try again’) with prescriptive microcopy that names the problem and prescribes the exact physical adjustment:
- Low-light guidance: ‘Move closer to the light. We can’t read the text on your ID yet.’
- Glare detection: ‘Tilt the card slightly. There’s a glare across your date of birth.’
- Framing & edge detection: ‘Pull back a little. The bottom edge is outside the frame.’
Every server rejection message you write is an admission that validation happened too late. Track document rejection rate as a first-class funnel metric alongside completion, and instrument which specific failure reason fires most often. Teams working to improve fintech UX routinely find that one or two capture conditions account for the bulk of rejections—and both are solvable with a smart camera overlay.
Step 4: How do you design for interruption with server-side save-and-resume?
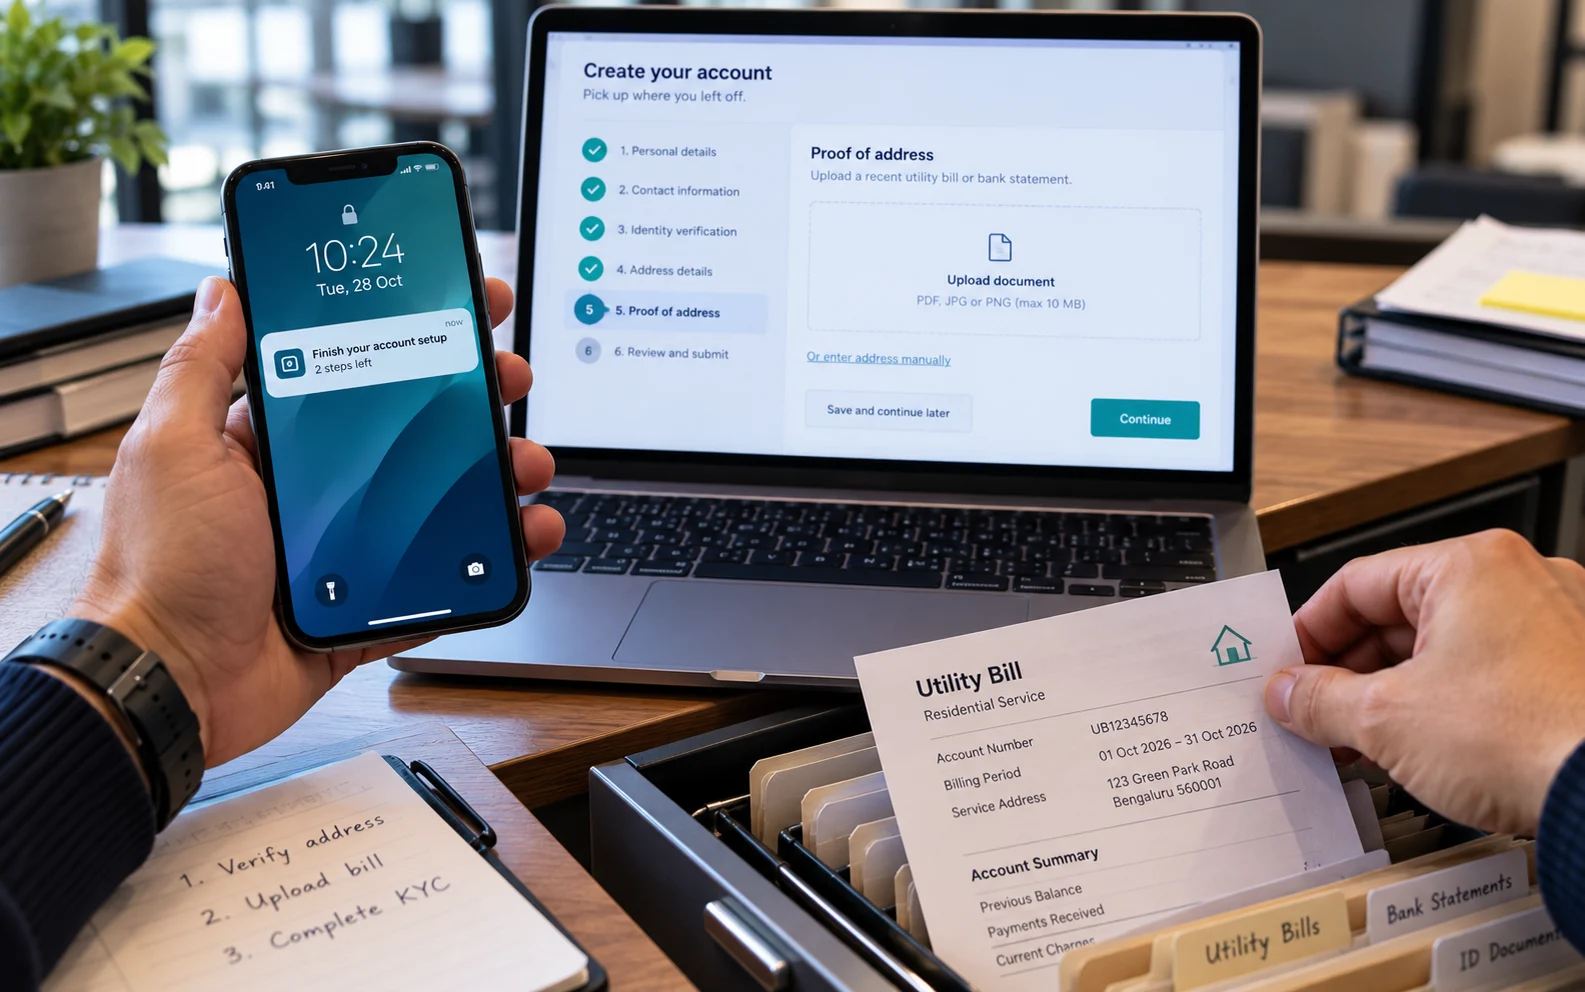
Design for interruption by treating session persistence as core infrastructure—saving progress at every completed field on the server and providing deep-linked multi-channel resumption paths. Fintech signup takes longer than social app signup because users get interrupted by a phone call or the realization that their proof of address is in a filing cabinet at home. The failure mode is treating a closed app as a terminated session and discarding what the user already typed.
- Persist state at every completed field, not every completed screen. A user who fills four of six fields and closes the app should return directly to field five.
- Store progress server-side, keyed to the account. Local device storage breaks the moment someone switches from phone to laptop to scan or upload a document.
- Deep-link push notifications to the pending step. A notification that drops a returning user on the generic home screen forces them to hunt; one that opens the exact outstanding verification screen converts.
- Send email reminders for cross-device bridging and state expiry clearly. Use email when the blocking task requires a desktop, and tell users clearly how long their saved progress is held so they do not restart from scratch.
Step 5: How does assisted onboarding and plain-language compliance build trust?
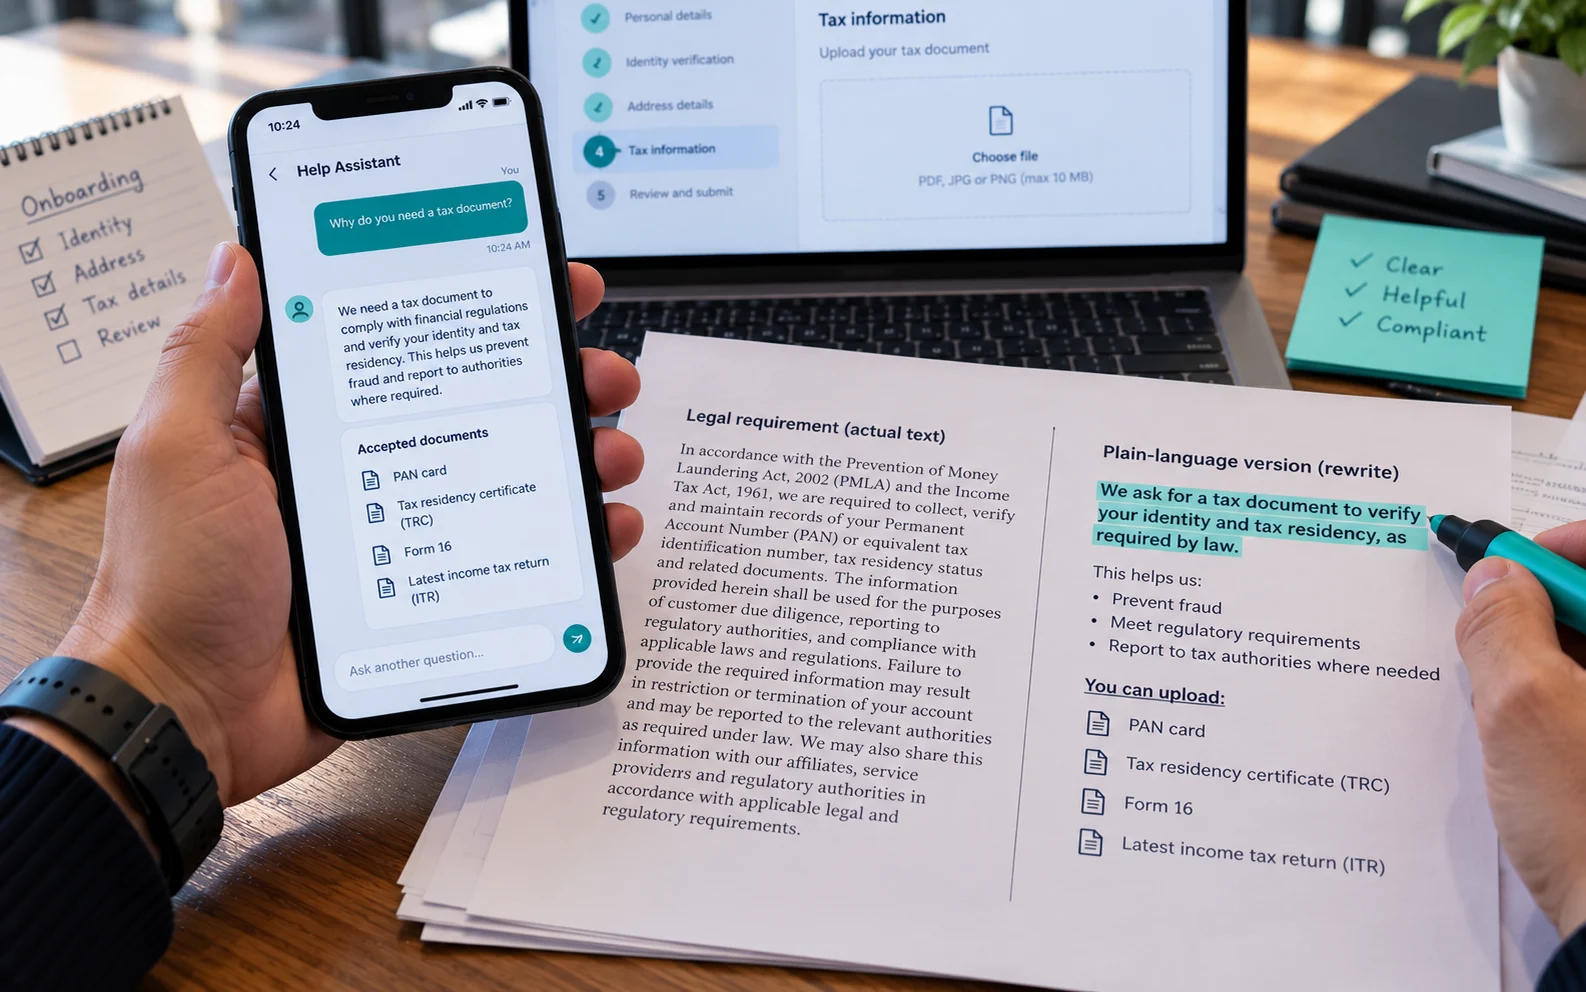
Assisted onboarding combines inline conversational support with plain-language regulatory explanations at the exact moment friction peaks. Because 37% of the U.S. population has already interacted with bank chatbots, offering an in-flow assistant to answer ‘Why do you need this tax document?’ or ‘Which utility bills are accepted?’ at the point of hesitation feels helpful rather than intrusive.
The teams winning at fintech conversion optimization have stopped treating compliance as the enemy of growth. Mandatory friction, sequenced intelligently and explained plainly, signals competence and security to a user handing over their financial identity. ScreenRoot designs the regulatory floor into the user journey from the first wireframe, which is the difference between an onboarding redesign that ships and one that stalls in legal review.
Step 6: How do you instrument and measure onboarding best practices in 2026?
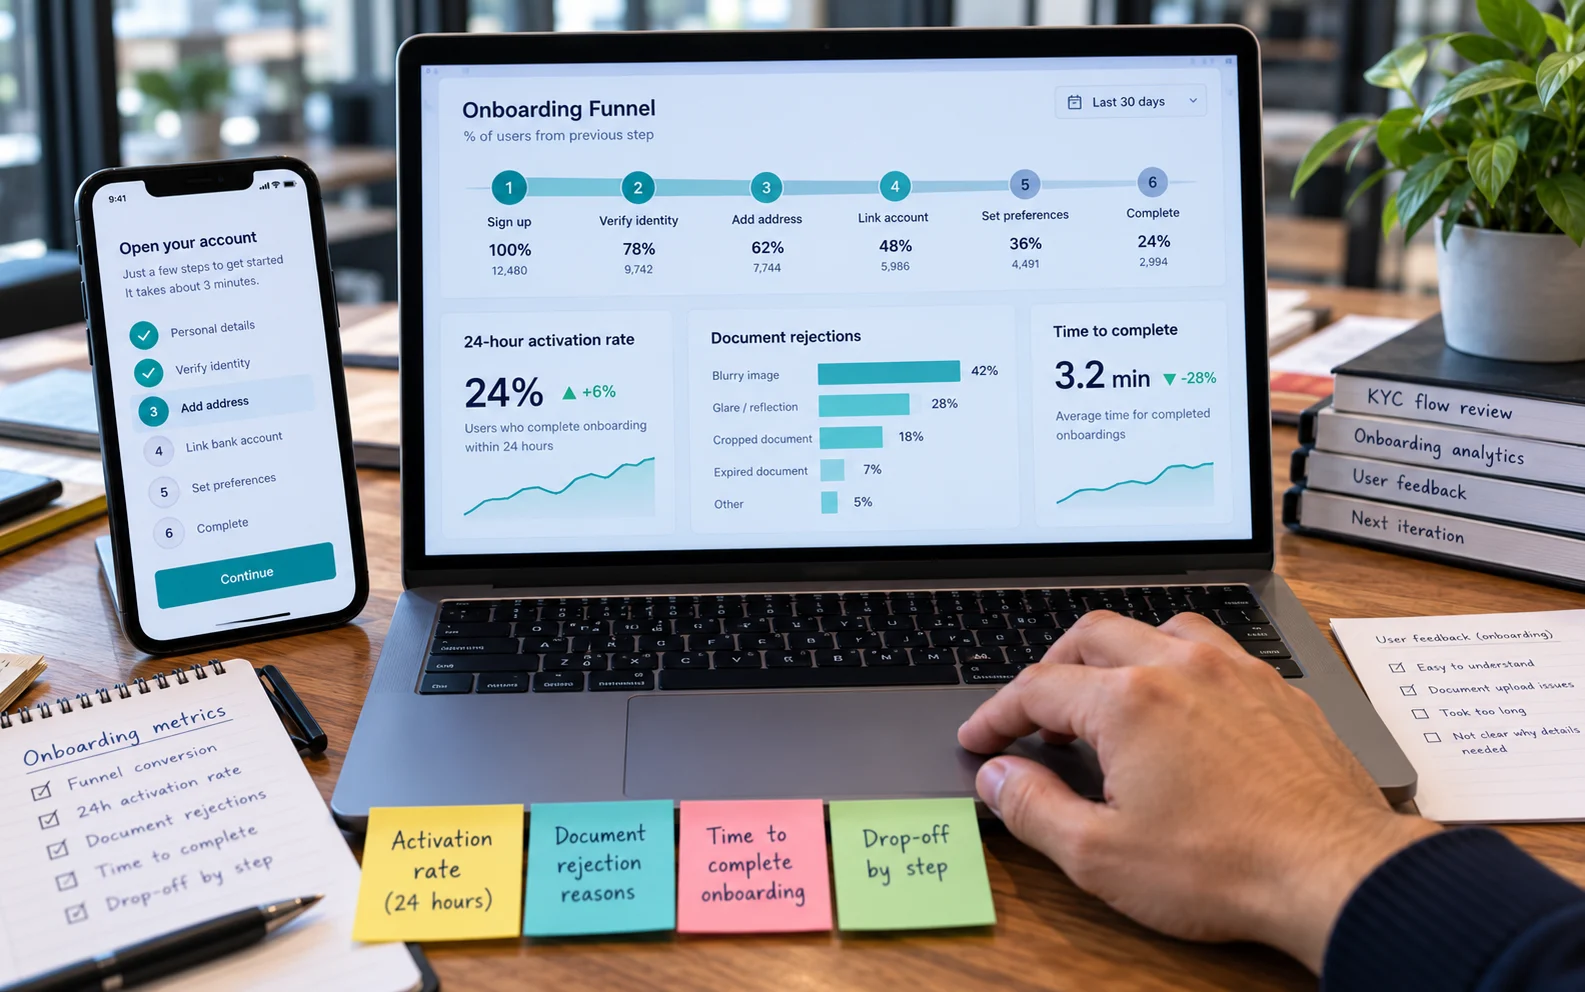
Judge your onboarding flow on what users accomplish, not on how many profile fields your database captures on day one. Before changing a screen, establish your baseline across four metrics:
- 24-hour activation rate: Percentage of new users reaching the named ‘Aha moment’ within 24 hours.
- Step-by-step and field-by-field drop-off: Where users stall, clear inputs, or abandon the flow.
- Document rejection rate by category: Percentage of ID or address captures failing due to blur, glare, or cropping.
- Interrupted session recovery rate: Share of paused signups that return via deep-linked push or email to finish KYC.
Onboarding best practices 2026 reward product leaders who instrument first and redesign second, proving which specific UX intervention moved which specific conversion number.
Frequently Asked Questions
Why do so many users abandon fintech app onboarding?
Users abandon fintech app onboarding primarily because apps demand too much non-essential segmentation data before showing any product value, reject ID documents after submission instead of validating camera framing in real time, and erase form progress when a user leaves the app to find a physical document.
What is the difference between hard and soft requirements in financial app onboarding?
Hard requirements are non-negotiable regulatory fields required for KYC/AML compliance—such as legal name, date of birth, government ID, sanctions screening, and tax ID. Soft requirements are optional product or marketing fields—like income brackets, investment goals, or attribution surveys—that should be deferred until after activation.
How does real-time document capture validation improve fintech conversion optimization?
By running blur detection, glare checks, and four-corner edge detection directly in the camera viewfinder before the shutter fires—paired with clear microcopy like ‘Tilt the card slightly to remove glare’—apps prevent bad uploads upfront and eliminate the #1 cause of KYC verification failure.
How should fintech apps handle users who pause signup mid-flow?
Save form progress server-side after every individual field (not just full screens), communicate clearly how long progress is saved, and send deep-linked push notifications or cross-device emails that return the user to the exact pending field or document upload step.
What is the best north-star metric for fintech app onboarding?
The best north-star metric is 24-hour time-to-value activation: the percentage of new users who complete the single core action that proves product value—such as linking a bank account, viewing a pre-approved credit limit, or sending a first transfer—within 24 hours of opening the app.
Turn your KYC funnel into a competitive advantage
If your acquisition spend is leaking out during identity verification or document capture, ScreenRoot can help you re-sequence your onboarding flow without compromising compliance. Explore our BFSI case studies at screenroot.com/work/ or request a diagnostic onboarding audit.
Written by Team ScreenRoot. 16+ years leading enterprise UI/UX research for BFSI, SaaS, and Healthcare clients
When you’re ready, let’s talk.
📞 Call us (Toll-Free): 1800 121 5955 (India)
✉️ Email us: [email protected]